Milestone Letter · The Gilding Trust · December 2027
A Life BuiltAgainst the Odds.
"The first draft was written when my bank balance showed only €958. That is the entrepreneur's posture: conviction in destination, discipline in the route, and patience with time."
Written by Nikolas G · Founder, Bitcoin Storm · Confidential — For Family
Scroll
A Personal Introduction
This letter has been a long time coming.
For years I chose not to send it — not because the message was uncertain, but because the right moment had not yet arrived. The first draft was written when my bank balance showed only €958. That is the entrepreneur's posture: conviction in destination, discipline in the route, patience with time.
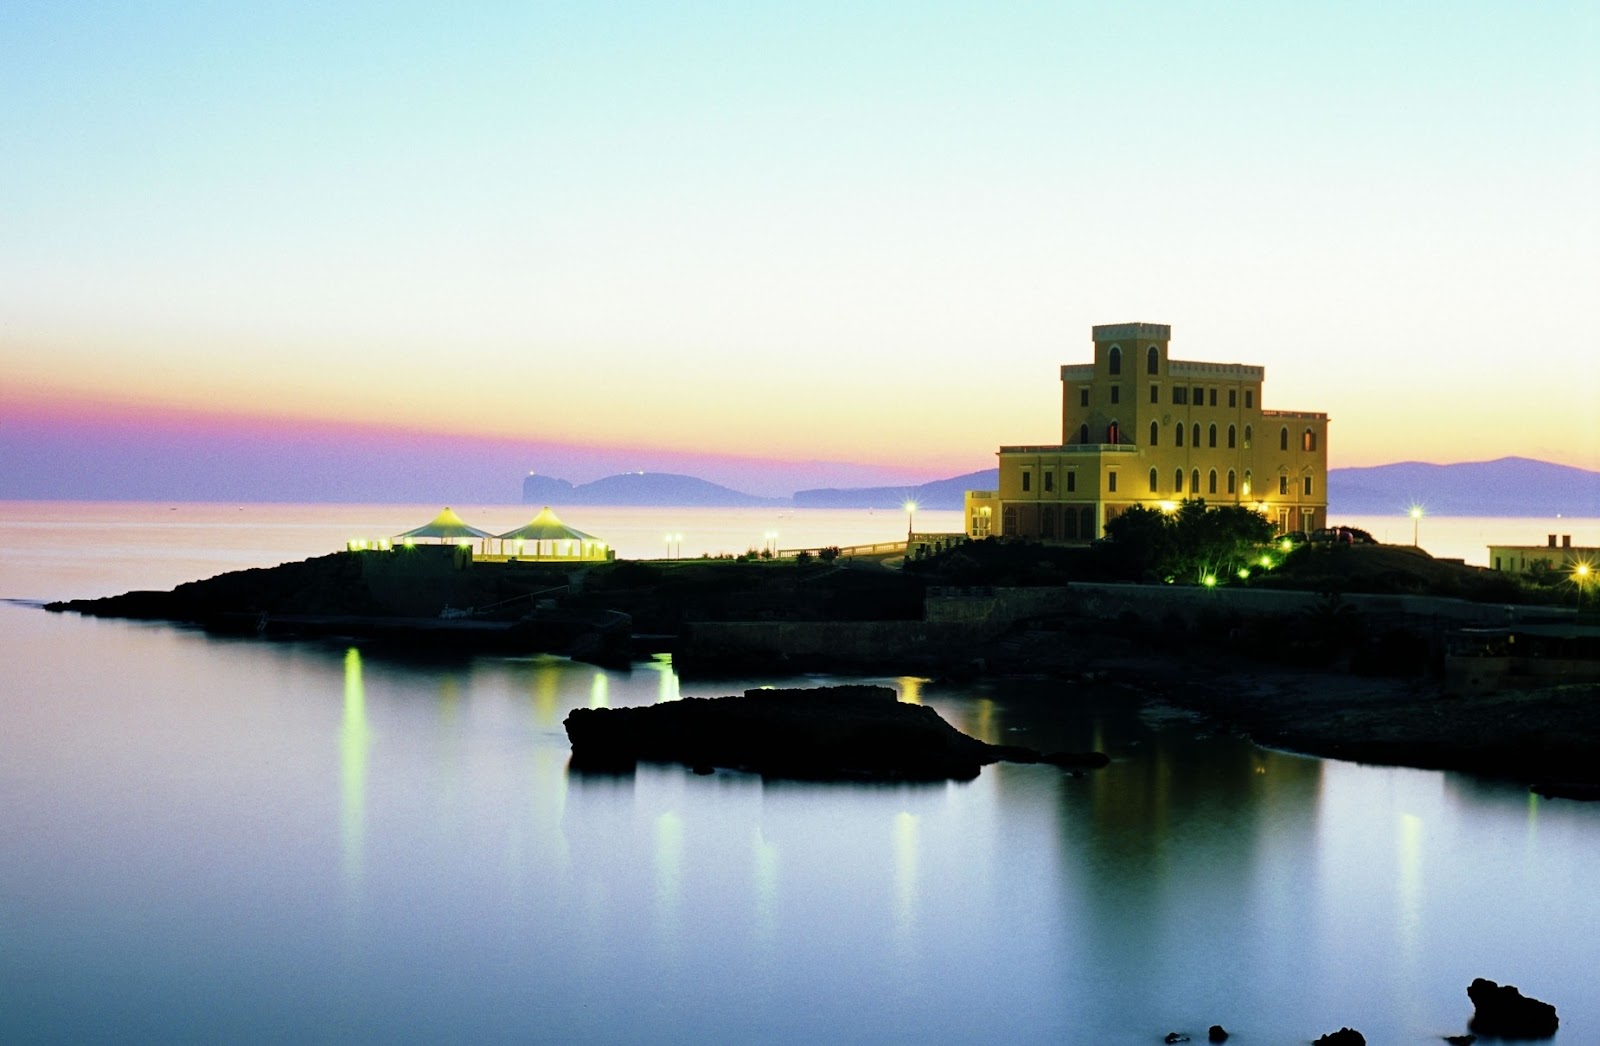
"There were days when I felt like giving up entirely. In those moments, I would reread this letter for encouragement and watch videos about Villa Las Tronas and the ISA superyacht collection — to remind myself what I was building toward. With renewed energy, I returned to the work and kept going."
What follows is written with clarity and calm. It is not a boast; it is a record. The journey was costly, imperfect, and at times deeply painful — but it was always deliberate. I share it now so that expectations are clear, boundaries are respectful, and our family can plan with real confidence.
A Milestone Worth Sharing
Persistence has finally had its answer.
My journey as an entrepreneur — combined with over four decades of share trading and relentless self-education in the crypto markets — has been anything but easy. To call it hard work would be an understatement. The road was filled with setbacks, miscalculations, and seasons where the gap between where I was and where I needed to be felt impossible to close.
After settling my Italian crypto tax obligations in full, I now sit comfortably between positions 250 and 300 on the UK Sunday Times Rich List — and the trajectory continues upward.
250–300
UK Rich List Position
40+
Years of Trading
2013
Crypto Entry Year
23×
Return on Capital
The Origin
One sentence in a discarded magazine changed everything.
Where It All Started
Fiumicino Airport, 2013.
In 2013, while Carla and I were waiting at Rome's Fiumicino Airport for her flight to Turkey, I picked up a technology magazine left behind on a seat. One sentence stopped me cold:
"Bitcoin has had a volatile year. Although it has been around for five years, it wasn't until 2013 that it caught most investors' attention. Excitement over the cryptocurrency even drove its price briefly above gold."
I read it three times. I folded the corner of the page. I did not put the magazine down for the rest of the wait. That afternoon at Fiumicino was not the beginning of a lucky break — it was the beginning of twelve years of study, failure, and eventual mastery of a system that most people still do not understand.
Bitcoin and Ethereum — A New Paradigm
From speculation to infrastructure.
I remember the moment clearly — page 14. A full-page article comparing Bitcoin to a new project called Ethereum. For the first time, I saw the two not just by price or popularity, but by purpose. Bitcoin was framed as digital gold: a decentralised store of value with a fixed supply, immune to inflation and government interference. Ethereum was introduced as something else entirely — programmable money, a platform for building decentralised applications, smart contracts, and entirely new financial ecosystems.
That comparison changed everything. It reframed the question from "should I buy Bitcoin?" to "where is the infrastructure of the next financial era being built?" That shift in thinking — from speculation to infrastructure — became the foundation of every significant position I ever took.
A High-Risk, Long-Term Bet
$100,000 on principle.
After exiting a Canadian mining deal, I found myself with significant liquid capital. Instead of rushing back into traditional markets, I paused. I dug deeper. Conversations with people exploring blockchain at the protocol level pushed me further down the rabbit hole — and what I found convinced me that this was not a speculative bubble, but the early formation of a new financial infrastructure.
I committed $100,000 to Bitcoin. It was a high-risk, long-term bet — not on price alone, but on principle. A calculated exposure to a decentralised future that I believed most of the world had not yet seen clearly. By early 2022, that position had grown substantially. Recognising the importance of risk management, I chose to exit — and began redeploying into a broader, more balanced portfolio across the emerging crypto ecosystem.
Time to Hire
Three traders. 23-fold return.
In August 2022, I brought on three exceptionally talented young crypto traders on a full-time basis — sharp minds with the instinct, hunger, and psychological resilience that this market demands and ruthlessly filters for. Over the following years, their strategy compounded with a consistency that is genuinely rare.
By mid-2027, the team had delivered a 23-fold return on my original capital. Remarkable by any conventional measure — yet in the context of crypto's most extraordinary performers, almost modest. Solana, Avalanche, and Shiba Inu each delivered multipliers that exceeded 500x from their early valuations. That contrast did not discourage me. It sharpened my conviction and confirmed a single belief: extraordinary results are achievable — if you understand the system and can identify the early signals before they become obvious.
The Decentralized Revolution
68 tokens in 2013. 16,900 by 2025.
My success is the product of several forces converging at the right moment: the 2026–2027 crypto bull cycle, the mainstream adoption of decentralised finance, and the accelerating convergence of Web 2.0 and Web 3.0 infrastructure. But none of that would have mattered without the foundation that was laid years earlier.
In those early years, timing and token selection were everything. Navigating exponential growth — separating genuine innovation from manufactured hype — required something that could not be shortcut: conviction, patience, and thousands of hours of diligent research. My strategy never chased trends. It pursued the question of where the future was heading — and positioned ahead of the answer.
The Journey — Losses, Lessons & Conviction
Every loss was a tuition fee.
Over three decades I took risks that would have paralysed most people. Not all of them worked.
EARLY DAYS
Scraped together €29,000 to start trading.Lost everything
SECOND ATTEMPT
Rebuilt and committed again.Lost €740,000
THE DARKEST POINT
Watched 90% of everything built to that point evaporate in a single cycle.Lost €4.8 million
2013
Discovered Bitcoin at Fiumicino. Began twelve years of deep research into crypto infrastructure.
FIRST BTC POSITION
Committed $100,000 to Bitcoin. High-risk, long-term bet — not on price alone, but on principle.Position held
AUGUST 2022
Brought on three exceptionally talented young crypto traders full-time.
MID-2027
The team delivered a 23-fold return on original capital.Extraordinary result
2027
The bull cycle, mainstream DeFi adoption and Web 3.0 convergence deliver the outcome.UK Rich List #250–300
The Light-Hearted Side
They missed the boat.
For as long as I can remember, I tried to pull my brother and sister into my world. With my sister, I would occasionally drop a casual hint — "things are going better than expected… I'll probably clear a few million" — hoping she would lean in with curiosity. Instead, she would almost always change the subject: "Must dash, that must be the doorbell."
With my brother: "If I told you I'd made £243M eight years ago, would you believe me?" The reaction was always the same. No spark. No questions. Just a shrug.
My parents used to say I wore blinkers — focused only on the road ahead, blind to distraction. For me, that was never a flaw. It was the whole point.
The Structure
A framework built to outlast a lifetime.
Financial Security for the Future
Effective 1 January 2028.
The Trust has ten beneficiaries: my brother, my sister, their six children, and the two babies born to my brother's sons. I have no children of my own, and so no grandchildren in the ordinary sense. These ten are what I have instead, and everything that follows is written for them.
Each of the ten will receive a one-time payment of £20 million, accompanied by a lifelong monthly income of £20,000 — adjusted annually in line with the UK Consumer Price Index — continuing until they reach the age of seventy-five. My brother and sister receive £40,000 a month rather than £20,000. That is not favouritism; it is arithmetic. They have fewer years ahead of them than the young ones, and a flat monthly figure would quietly hand them a fraction of the same provision.
Any child born into the family afterwards is added automatically, on the same terms, with payments commencing on the first January following their birth. No one is left out, and no one has to be asked for.
Where a beneficiary is under eighteen, the entitlement exists in full from the outset but is held by the trustee until they come of age. The monthly income is applied for their benefit in the meantime — education, housing, whatever their circumstances genuinely require — and the capital passes into their own hands on their eighteenth birthday. This is not a test of character or a condition to be satisfied. It is simply that a child cannot hold £20 million, and someone sensible has to look after it until they can.
💷
£20,000,000
One-time capital payment per beneficiary, effective 1 January 2028. A foundation from which each person can build whatever they choose — without the weight of financial anxiety pressing on every decision.
📅
£20,000 / month
Lifelong monthly income, adjusted annually in line with the UK Consumer Price Index. Payments continue until each beneficiary reaches the age of seventy-five — genuine security across the entirety of adult life.
👨👩👧👦
Ten Beneficiaries
My brother, my sister, their six children, and two babies — with every child born into the family afterwards added automatically on the same terms, payments commencing on the first January following their birth. No one is left out.
🤝
£40,000 / month — Brother & Sister
My brother and sister take the same £20 million as everyone else, with the monthly figure set at £40,000. Fewer years to seventy-five means fewer payments; the higher rate simply brings the total into line with what the younger beneficiaries will receive over a longer life.
The Gilding Trust
Exclusivity. Legacy. Opportunity.
The Gilding Trust is more than a financial structure — it is a gateway to a world that very few people ever access. Beneficiaries enjoy privileged access to an extraordinary portfolio of assets: historic estates, flagship superyachts, and holdings that will continue to grow in both value and scope.
Whether it is a private week at a royal Sardinian retreat, a champagne evening on the deck of a 70-metre yacht at anchor off the Amalfi coast, or the quiet confidence that comes from knowing the next generation is genuinely provided for — the Trust was built to make those things real.
"The structure I have built is designed precisely to interrupt that pattern — to create a framework robust enough to protect our family's position across generations."
Belief and Support
Carla was different.
Carla is my partner, and has been through most of what this letter describes. She met me long before there was anything to be met for.
Between 2006 and 2010 — some of the hardest, most uncertain years of my life — she gave me a quarter of her post-tax salary. No collateral. No repayment schedule. No guarantees. Just trust in my determination. There were moments where she admitted, quietly, that she could not see how I would ever get there. My answer was always the same word: never.
Today, Carla holds £25 million, provided for outside the Trust and independently of it. Some of you may notice that this is more than any single beneficiary receives, and I would rather explain it now than leave it to be wondered about. She backed me when doing so cost her something real, at a time when nobody else would. That is the whole of it.
Trust Incorporation
A statement of accountability.
To proactively address any concerns regarding the origins of my recent financial gains — particularly given my past convictions — I have taken deliberate steps to ensure full compliance and transparency. I have engaged one of the United Kingdom's most respected trust management firms to oversee the creation and governance of a UK-registered trust.
This structure uses existing inheritance tax and gifting legislation to provide each beneficiary with secure, tax-efficient income throughout their lifetimes. Establishing such a trust requires extensive due diligence — comprehensive proof of earnings, rigorous anti-money laundering checks, and independent legal verification at every stage. This is not merely a vehicle for wealth preservation. It is a commitment to building a legacy that will withstand scrutiny, survive time, and serve our family well beyond my own lifetime.
The Capital Architecture
The size of the pool, by the numbers.
The numbers above — £20 million per beneficiary, £20,000 per month (£40,000 for my brother and sister), ten beneficiaries — are not arbitrary. They are the inputs to a perpetuity formula. The income capital pool is sized so that its annual yield exactly funds the monthly payments, with the principal never touched. Adjust any input and the total capital required moves with it.
One honest caveat sits underneath all of it. Every figure here assumes a 2% real yield — that is, 2% above inflation — held steadily across half a century. That is a deliberately conservative assumption, and the £50 million reserve exists precisely to absorb the years when markets do not cooperate. But no one can promise fifty years of anything. The trustee's first duty is to the monthly income, ahead of the reserve and ahead of the lump sums; if conditions ever made these terms genuinely undeliverable, the trustee is required to say so plainly and to adjust rather than to spend the Trust into nothing keeping up appearances. I would rather you heard that from me now than discovered it later.
The calculator below lets you see it. Pull the sliders and watch the figures move. The base case at the top — ten beneficiaries, £20M lump, £20K monthly (£40K for my brother and sister), a 2% real yield, plus a £50M reserve — produces the total capital figure on which the Trust deed is built.
Interactive · Pull the sliders
Capital Requirements Calculator
Four inputs determine the total. Beneficiaries set the scale. Yield sets the income pool's size — the lower the yield, the more capital is required to generate the same payment. Lump sum and monthly income set what each beneficiary receives.
1Beneficiaries
10
10 — 17
2Real annual yield
2.0%
1% — 4%
3Lump sum per beneficiary
£20M
£0 — £20M
4Monthly income per beneficiary
£10K
£0 — £25K
Include £50M reserve & contingency
Total capital required
£394M
— for 10 beneficiaries at 2.0% real yield (incl. £50M reserve)
The full architecture — the yield sensitivity scenarios, the beneficiary schedule, the newborn provisions, the investment mandate, the UK trust law analysis, the inheritance tax taper, and the ten-step establishment process — sits in the linked document above. That document is the work product the Trust solicitor builds on. This letter tells you what the Trust does. The document tells you exactly how it is engineered.
Looking Ahead to the Future
70% of wealthy families lose it by generation two.
My focus now is firmly on capital preservation and the long-term security of the Gilding family. The oft-cited statistic — that 70% of wealthy families lose their wealth by the second generation, and 90% by the third — is not a curiosity. It is a pattern with well-documented causes: poor governance, absence of financial discipline, entitlement, and the erosion of the values that built the wealth in the first place.
I take this seriously. The structure I have built is designed precisely to interrupt that pattern — to create a framework robust enough to protect our family's position across generations, regardless of the individual decisions made by any single member along the way.
A Gift of Great Pleasure
A meaningful head start.
It brings me genuine joy to give the young ones in this family a meaningful head start. A foundation built not just on money, but on intention — the deliberate choice to pass forward something real and lasting, rather than leaving them to start from scratch the way I had to.
Knowing they will have the security to explore their own paths, to take their own risks without existential fear, is one of the most satisfying outcomes of everything I have worked for. For my brother and sister — both already financially stable — I hope the additional support brings a measure of extra freedom in the years ahead. It is a gesture of family, of shared history, and of the quiet recognition that loyalty takes many forms.
Cushion and Springboard
£20 million is transformative capital.
I understand there may be some who view £20 million as a modest figure relative to the scale of what has been built. I would ask those people to sit with that figure for a moment before reaching that conclusion. £20 million is transformative capital in almost any context. It is enough to eliminate financial anxiety permanently, to fund a serious business venture, to provide housing security for a lifetime, or to build a meaningful investment portfolio that compounds over decades.
The question is never about the number in isolation — it is about what the recipient chooses to do with it. That is the variable I cannot control. What I can control is providing a platform that is genuinely generous and genuinely real. What happens next is up to each individual.
On Gambling and Taking Chances
Discipline over speculation.
Cryptocurrency trading is undeniably volatile — often compared to the Wild West for its absence of regulation and the prevalence of bad actors. That comparison is not entirely unfair. I have seen fortunes built and destroyed in the space of a single quarter. I have watched brilliant people lose everything to overconfidence, and cautious people miss extraordinary opportunities through excessive hesitation.
For those who approach it with genuine discipline, deep research, and the psychological resilience to hold conviction under pressure, the potential is real. My hope is that this gift serves as both cushion and launchpad — providing security while also creating the freedom to back yourself when the right opportunity presents itself.
Dreaming Beyond Today
The capital is in your hands.
Whether you are dreaming of the larger house with the boat and the pool, thinking seriously about finally acquiring the restaurant you have managed so well — now that it is available — or simply feel that £40 million sounds considerably more comfortable than £20 million: the capital is in your hands. It can be the beginning of something far bigger.
If you want to climb further, you have what you need to begin. I would rather watch one of you build something of your own with this than see it sit untouched in an account — though that choice, too, is entirely yours to make.
Family Potential — Another Nik
Perhaps there is another way.
If I knew then what I know now, I am not sure I would have taken the same path. The personal cost was extraordinary — higher than I would wish on anyone I care about. I was convicted and sent to prison three times. I did not learn after the second. I had a blatant disregard for financial law and no hesitation in breaking it — not because I was unaware of the consequences, but because I had decided that getting to where I needed to go mattered more than anything else. That arrogance caused real damage to real people. It is not something I am proud of.
When I look at this family now, I do not see those same tendencies — and perhaps that is not a loss. Perhaps it is possible to build something genuinely significant, play with integrity, treat people with fairness, and still arrive somewhere extraordinary. That would be a far better story than mine. I would welcome it.
The Personal Cost
The boundary is clear.
One practical note, said once and then left alone. What is in this letter is what there is. It is not a first instalment or an opening position, and I would ask that it not be treated as one. Setting that out plainly now seems kinder than leaving it to be discovered later, in a conversation neither of us would enjoy.
The journey that produced this came at a cost that does not appear on any balance sheet, and I have no wish to describe it at length. It is enough to say that I would like the years ahead to be spent as a grandfather rather than as a source of funds. What sits in this letter is substantial. What comes after it is yours to build.
Retirement, Wealth, and Stress
Preserving sanity as much as capital.
The gifts in this letter were structured to be complete in themselves — enough that no one need come back for more, and clear enough that no one need wonder where they stand. Substantial wealth brings its own complications. It tends to attract a steady stream of investment pitches, lending requests, and well-meaning suggestions from people who suddenly find themselves interested in what you are doing.
I have no desire to revisit that chapter from the opposite direction. That is why I chose to place my wealth under independent, arm's-length management. The structure covers my living costs, maintains the assets, and protects the remainder. It is not just about preserving money — it is about preserving sanity, and staying honest about my own compulsive tendencies when it comes to high-risk decisions.
Who the Trust Is For
You are in. That part is settled.
Significant wealth brings a question that is more subtle than it first appears: who is entitled to enjoy its benefits, and on what basis? I have settled it in the simplest way available to me. Everyone is entitled. All ten are named in the deed, every child born into the family afterwards is added automatically, and there is no membership to accept and none to refuse. The Villa Las Tronas, the vessels, the concierge and advisory services of the Trust — these belong to the beneficiaries, and you are one of them whether or not you ever request a single pound.
What remains yours to decide is narrower, and far more sensible: how much you draw, and when. That is a decision you may make, and remake, for the rest of your life.
Flagship Holdings
Three assets. One vision.
These three assets were not chosen at random. The superyachts represent the freedom I was always working toward — the open sea, on your own terms. The hotel is the Sardinian coast that kept me going in the dark years, when I watched those videos to remind myself what I was building toward.
🏨 Villa Las Tronas Hotel & Spa
€20,000,000
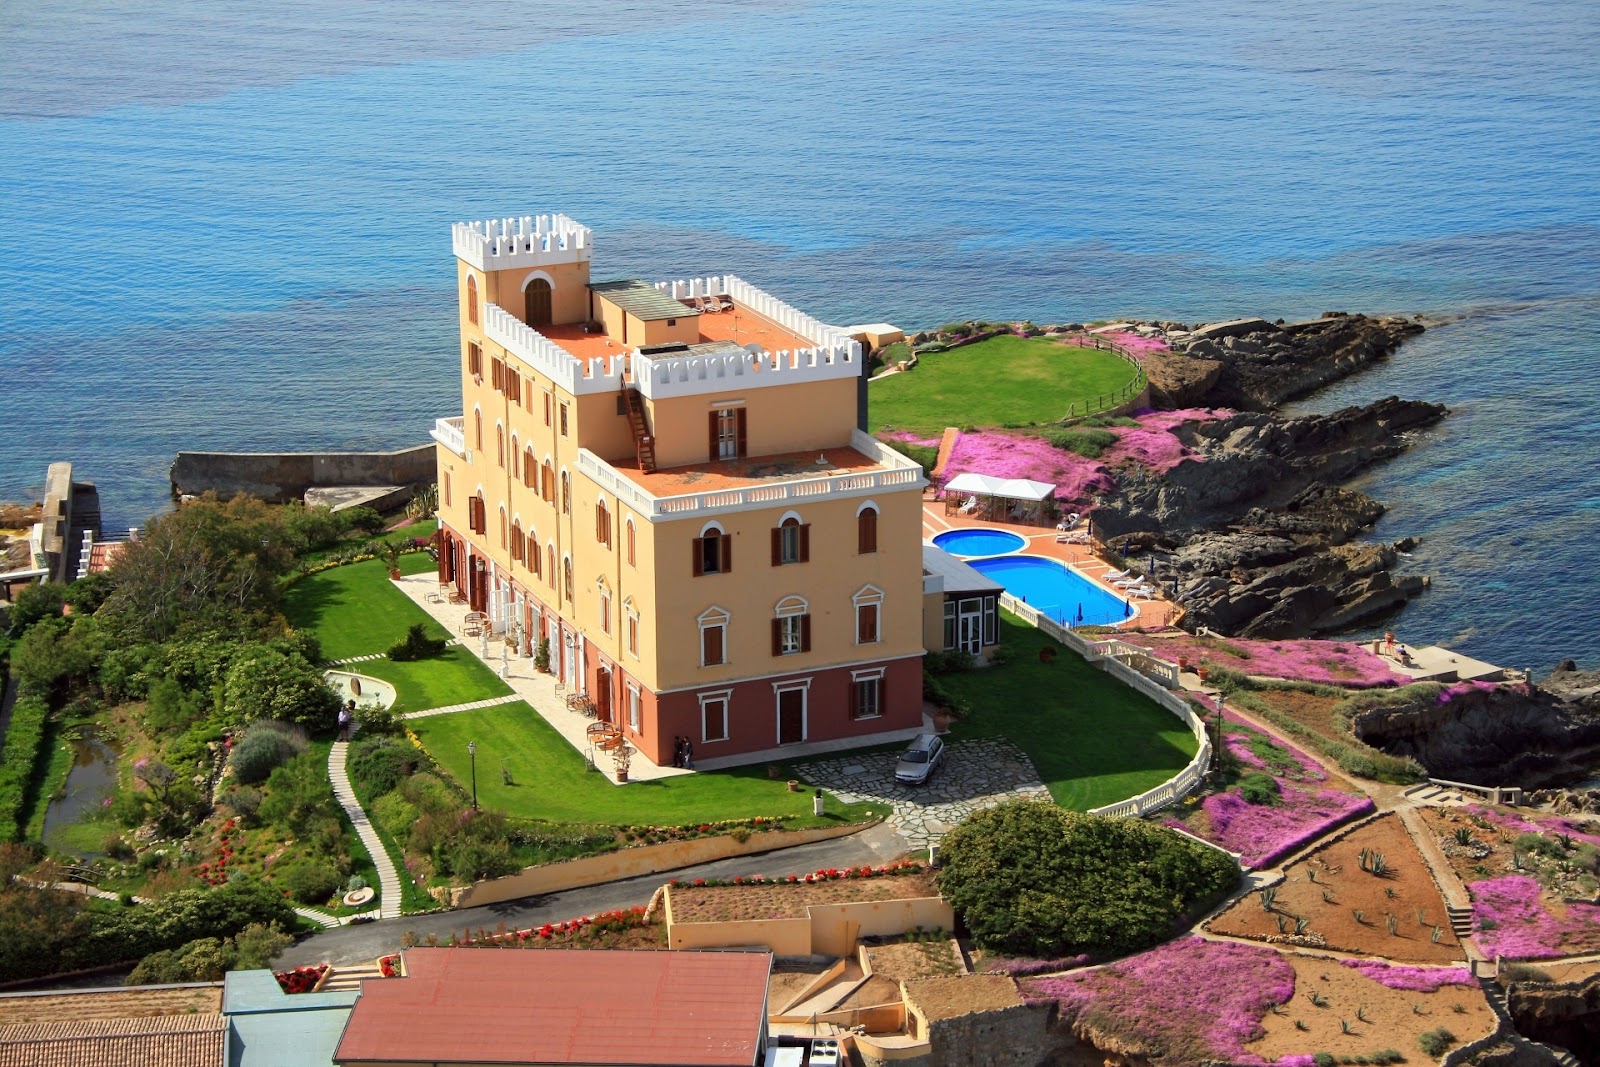
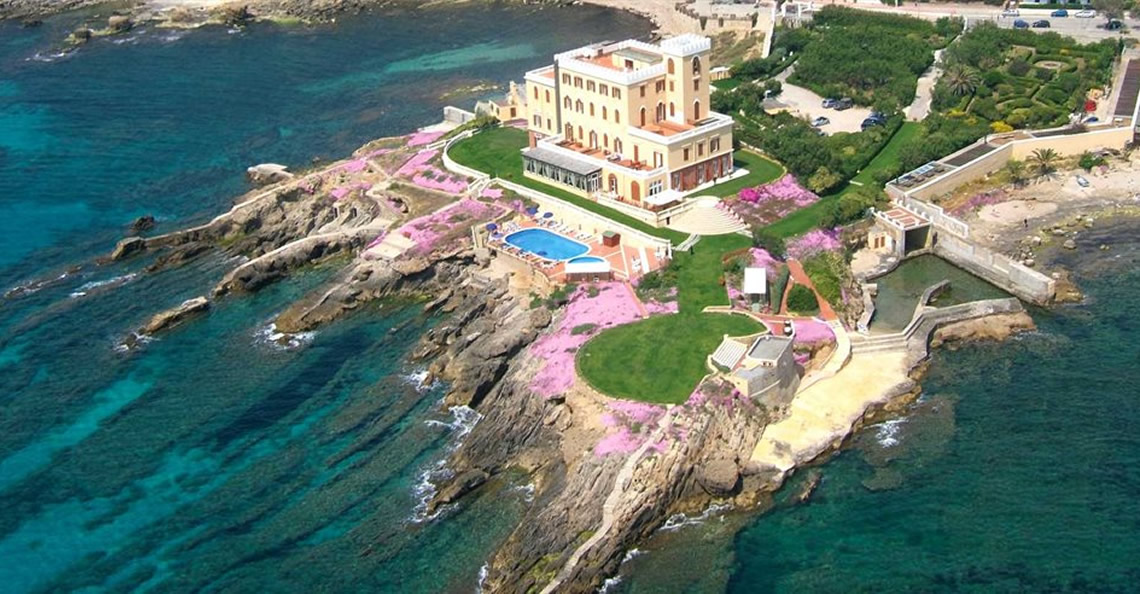
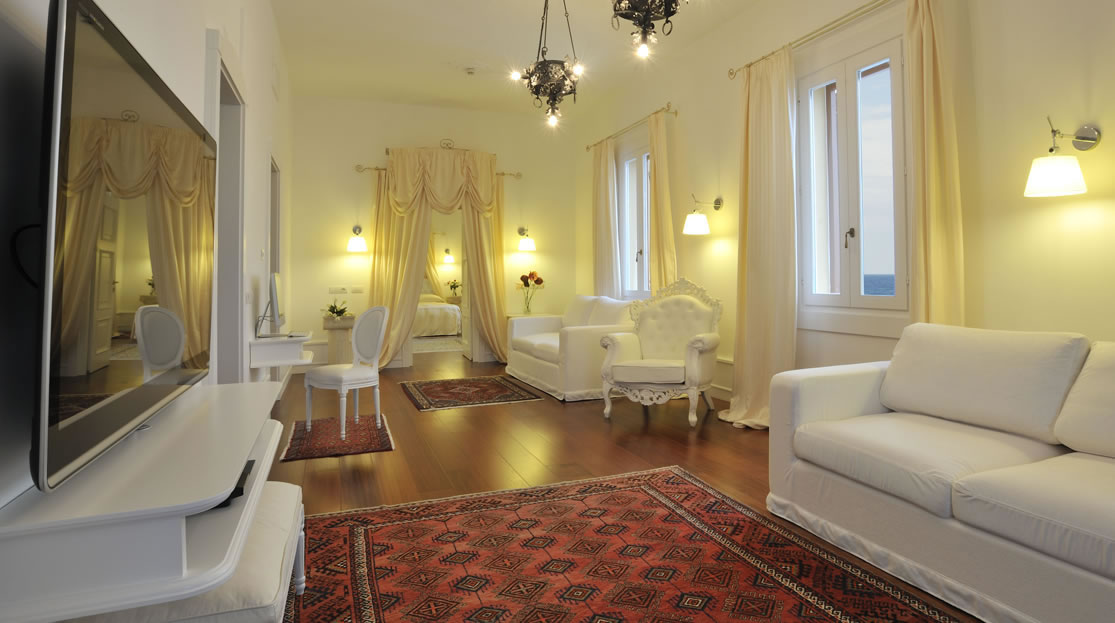
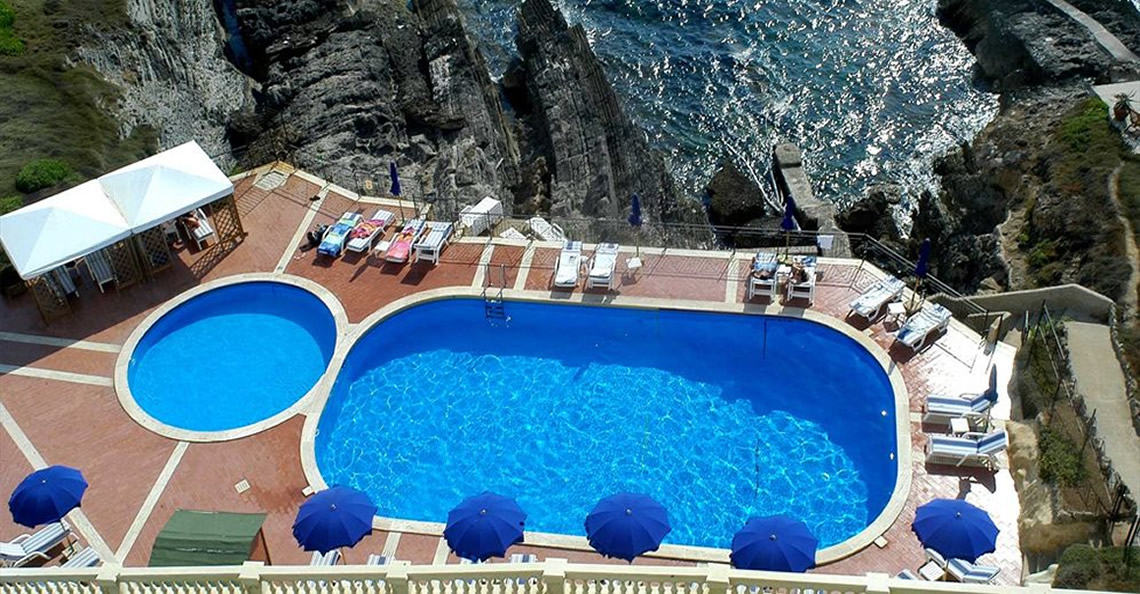
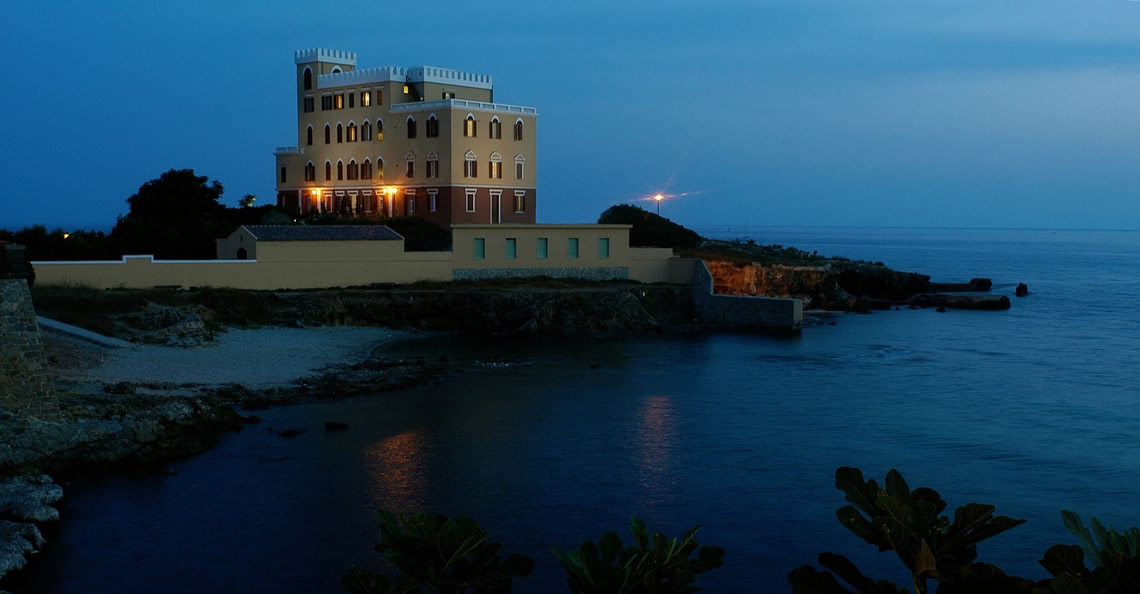
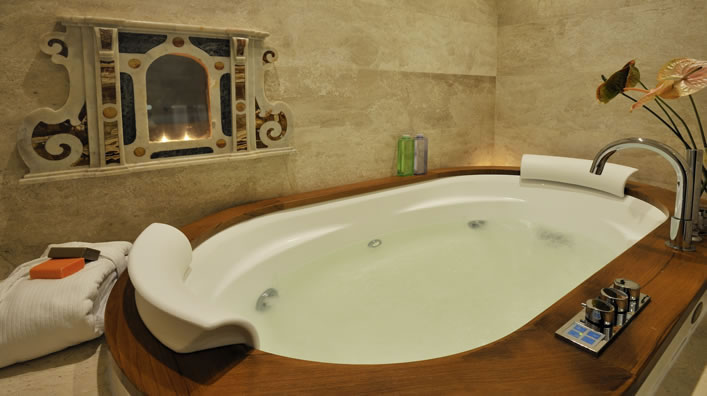
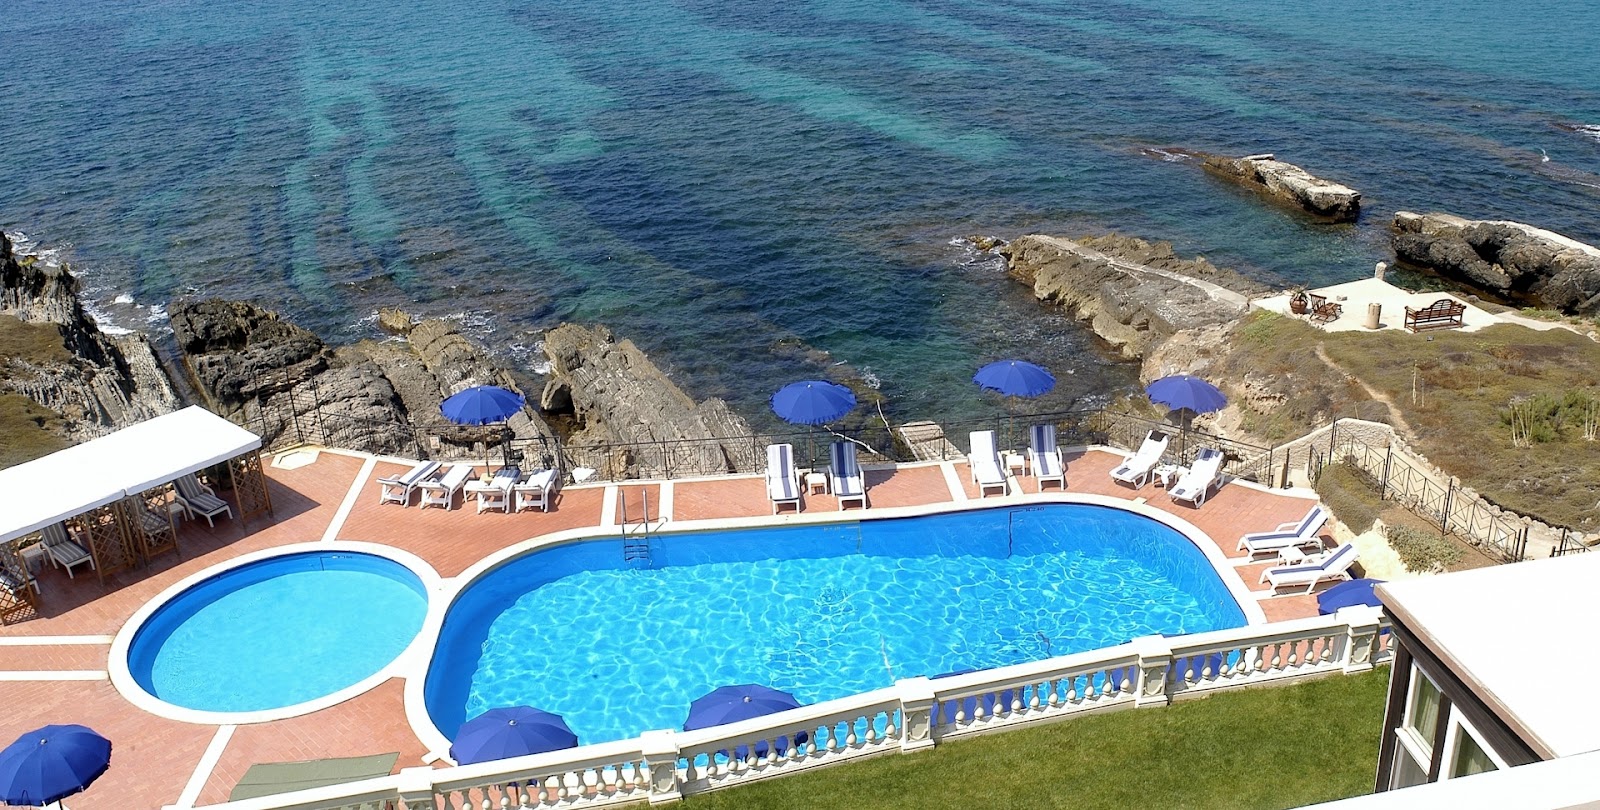
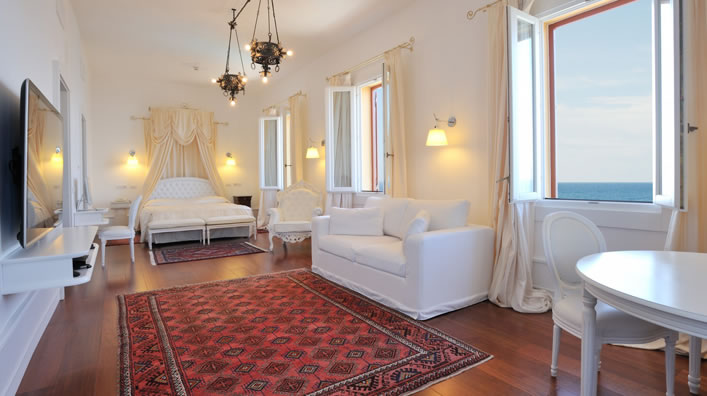
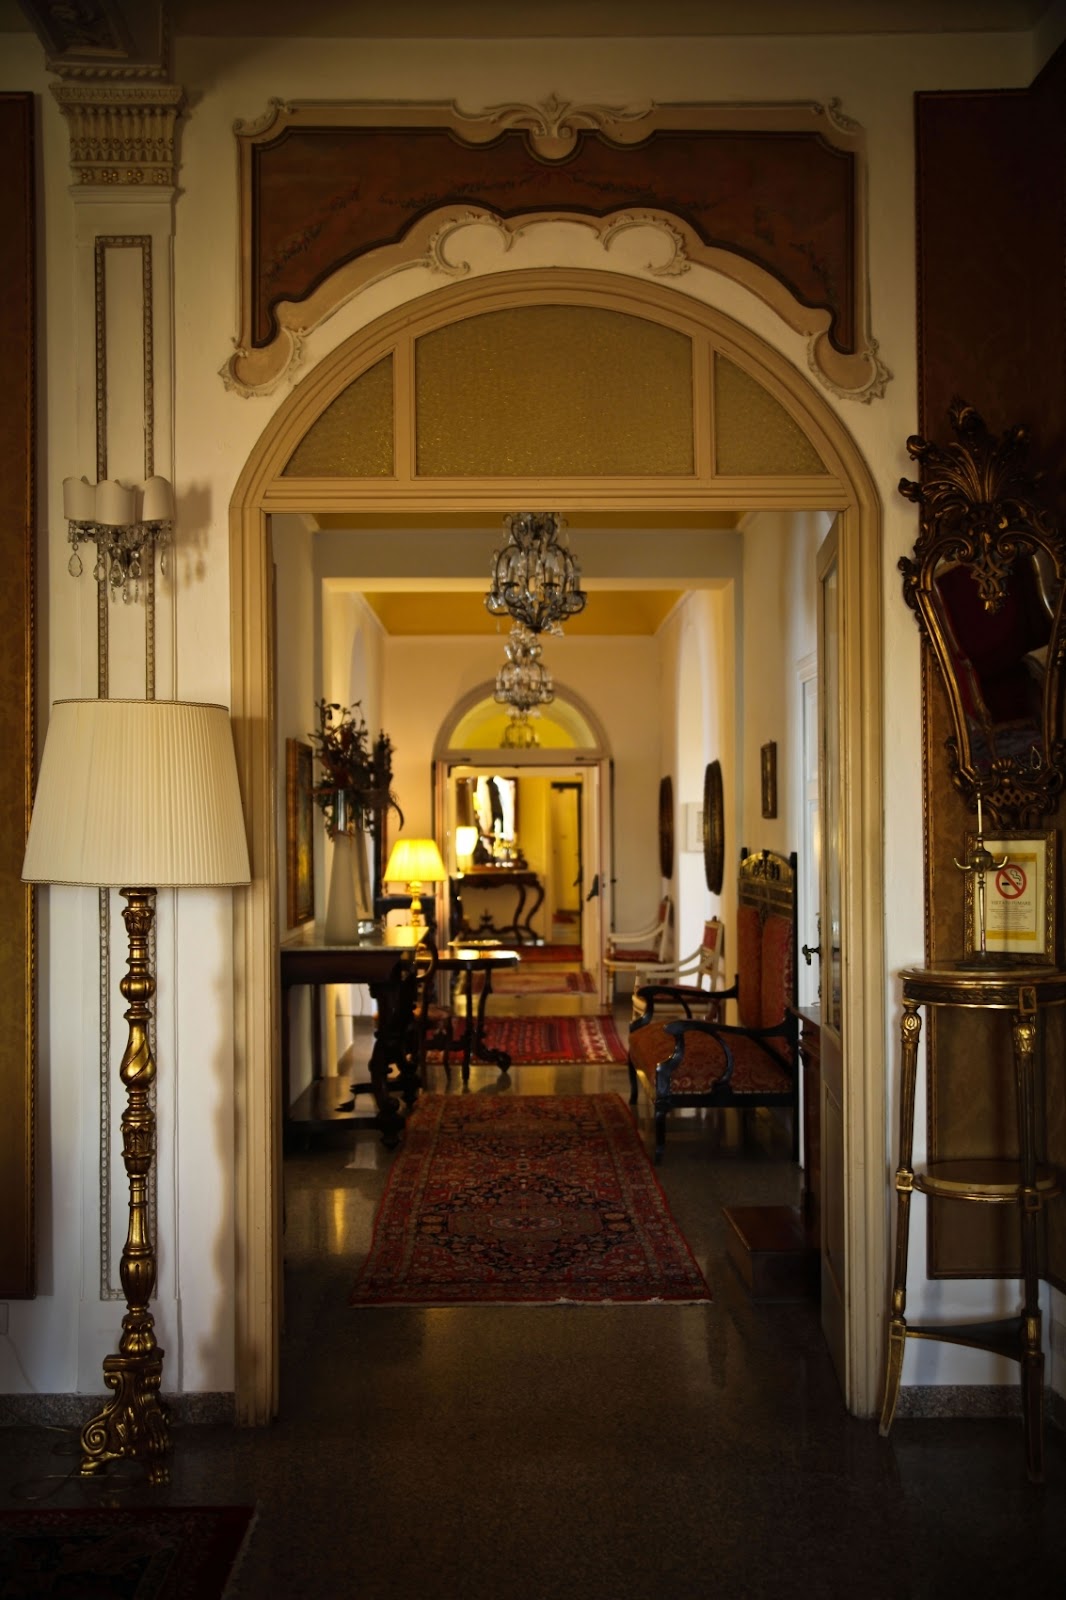
Built in 1880 by Alessandro, the third Count of Sant'Elia, and later a favourite retreat of the Italian Royal Family until the 1940s — Villa Las Tronas is one of the most singular private estates in Italy, its ancient walls reaching directly to the sea. Perched on its own rocky promontory between Cala Lavatoio and Cala Capone, surrounded on three sides by the crystalline waters of Alghero's gulf — named by many the most beautiful in the Mediterranean.
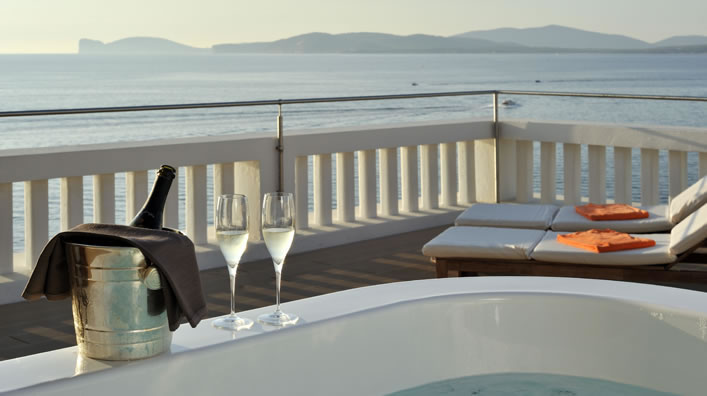
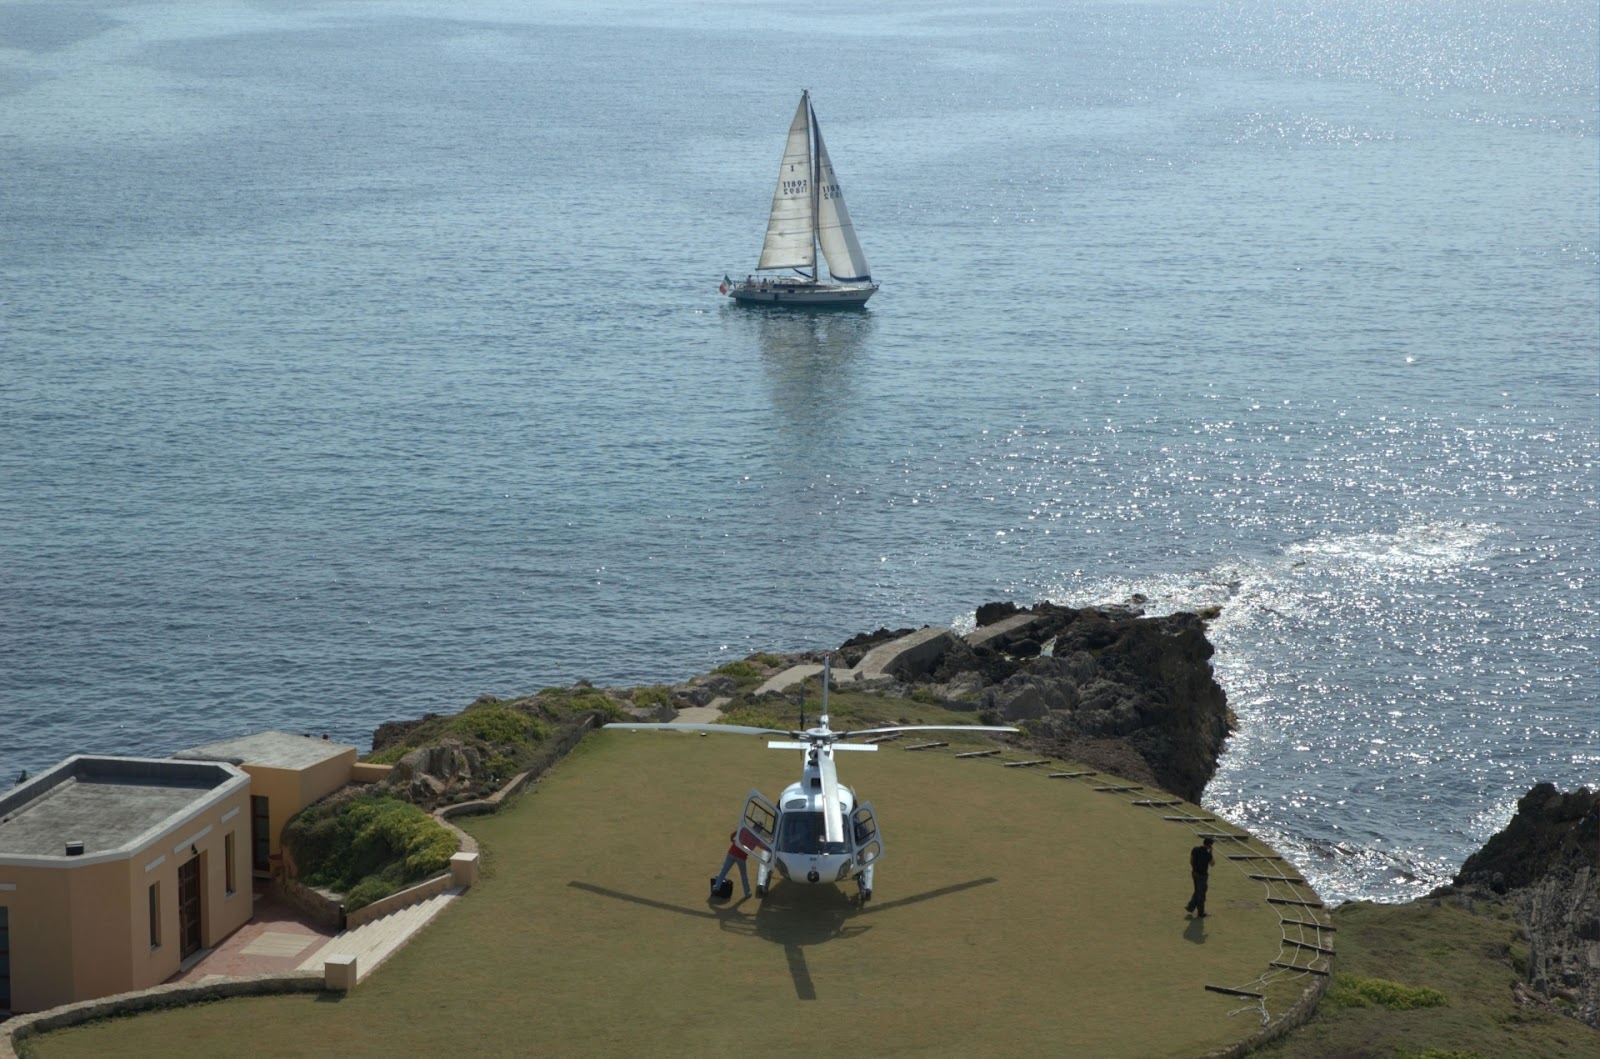
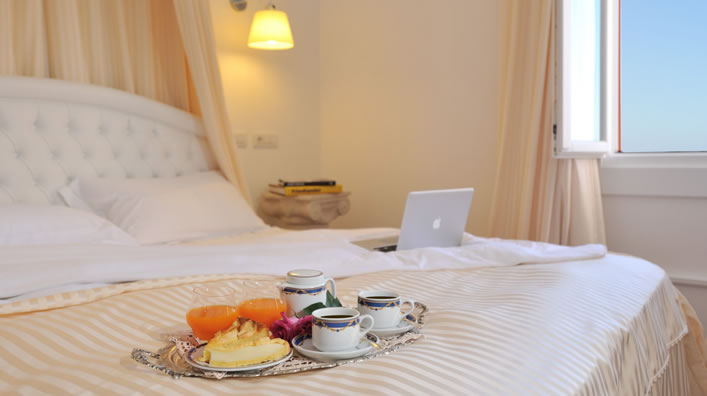
A five-star hotel of just 25 individually appointed rooms and suites. Indoor heated seawater pool, sauna, hammam, full wellness programme. Panoramic restaurant with strictly seasonal Sardinian cuisine. Private harbour and helipad. Guests have included Antoine de Saint-Exupéry, Liz Taylor, and Richard Burton.
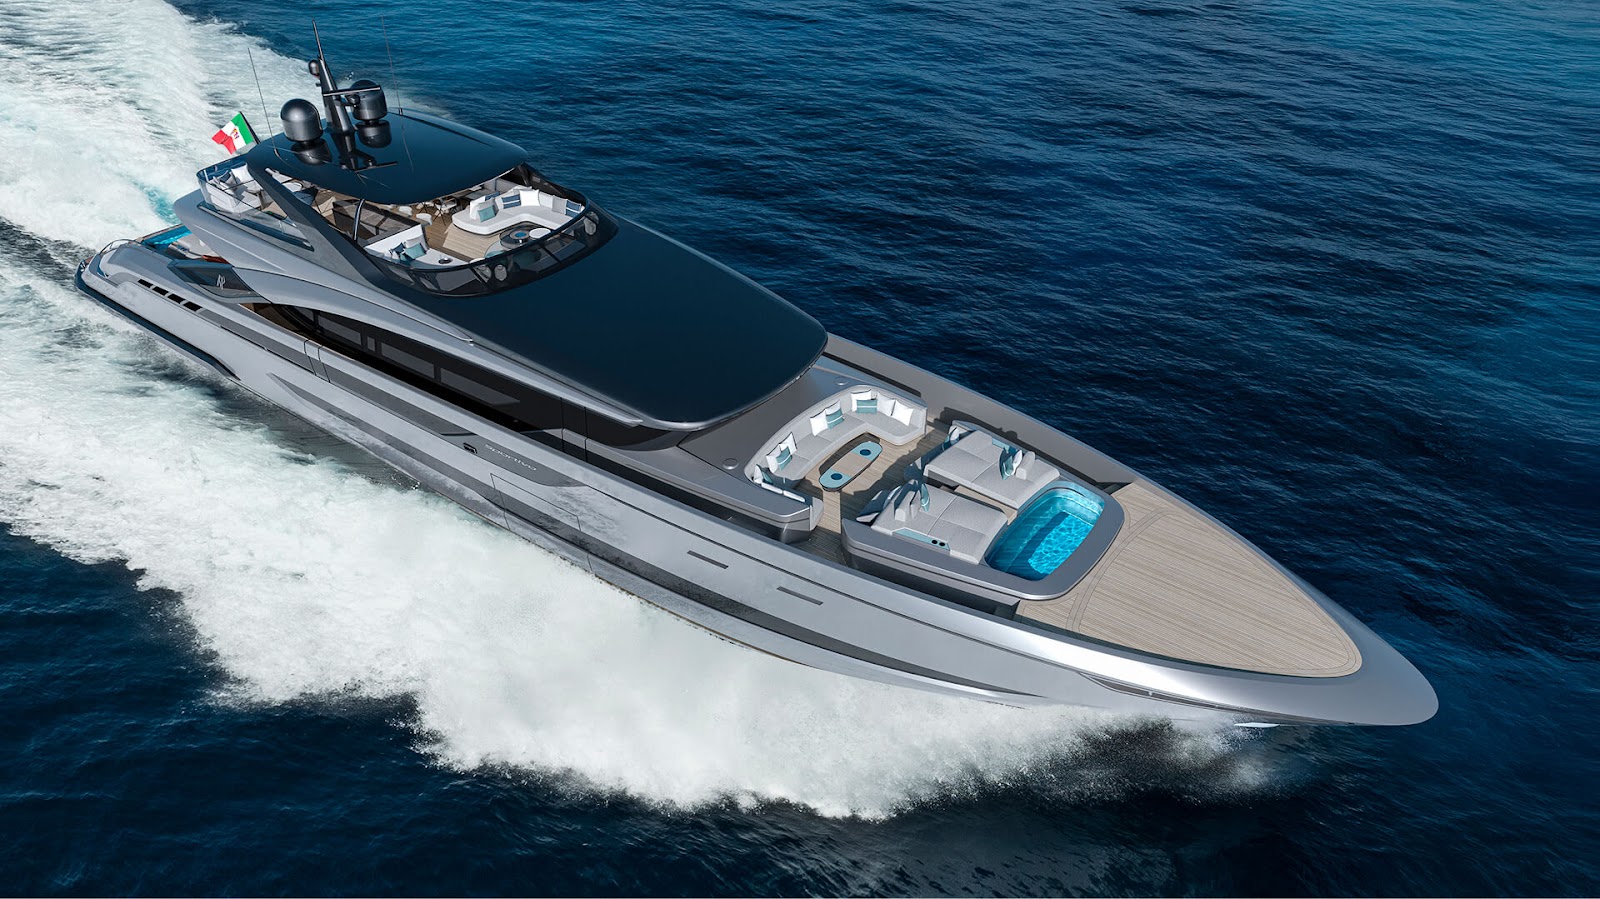
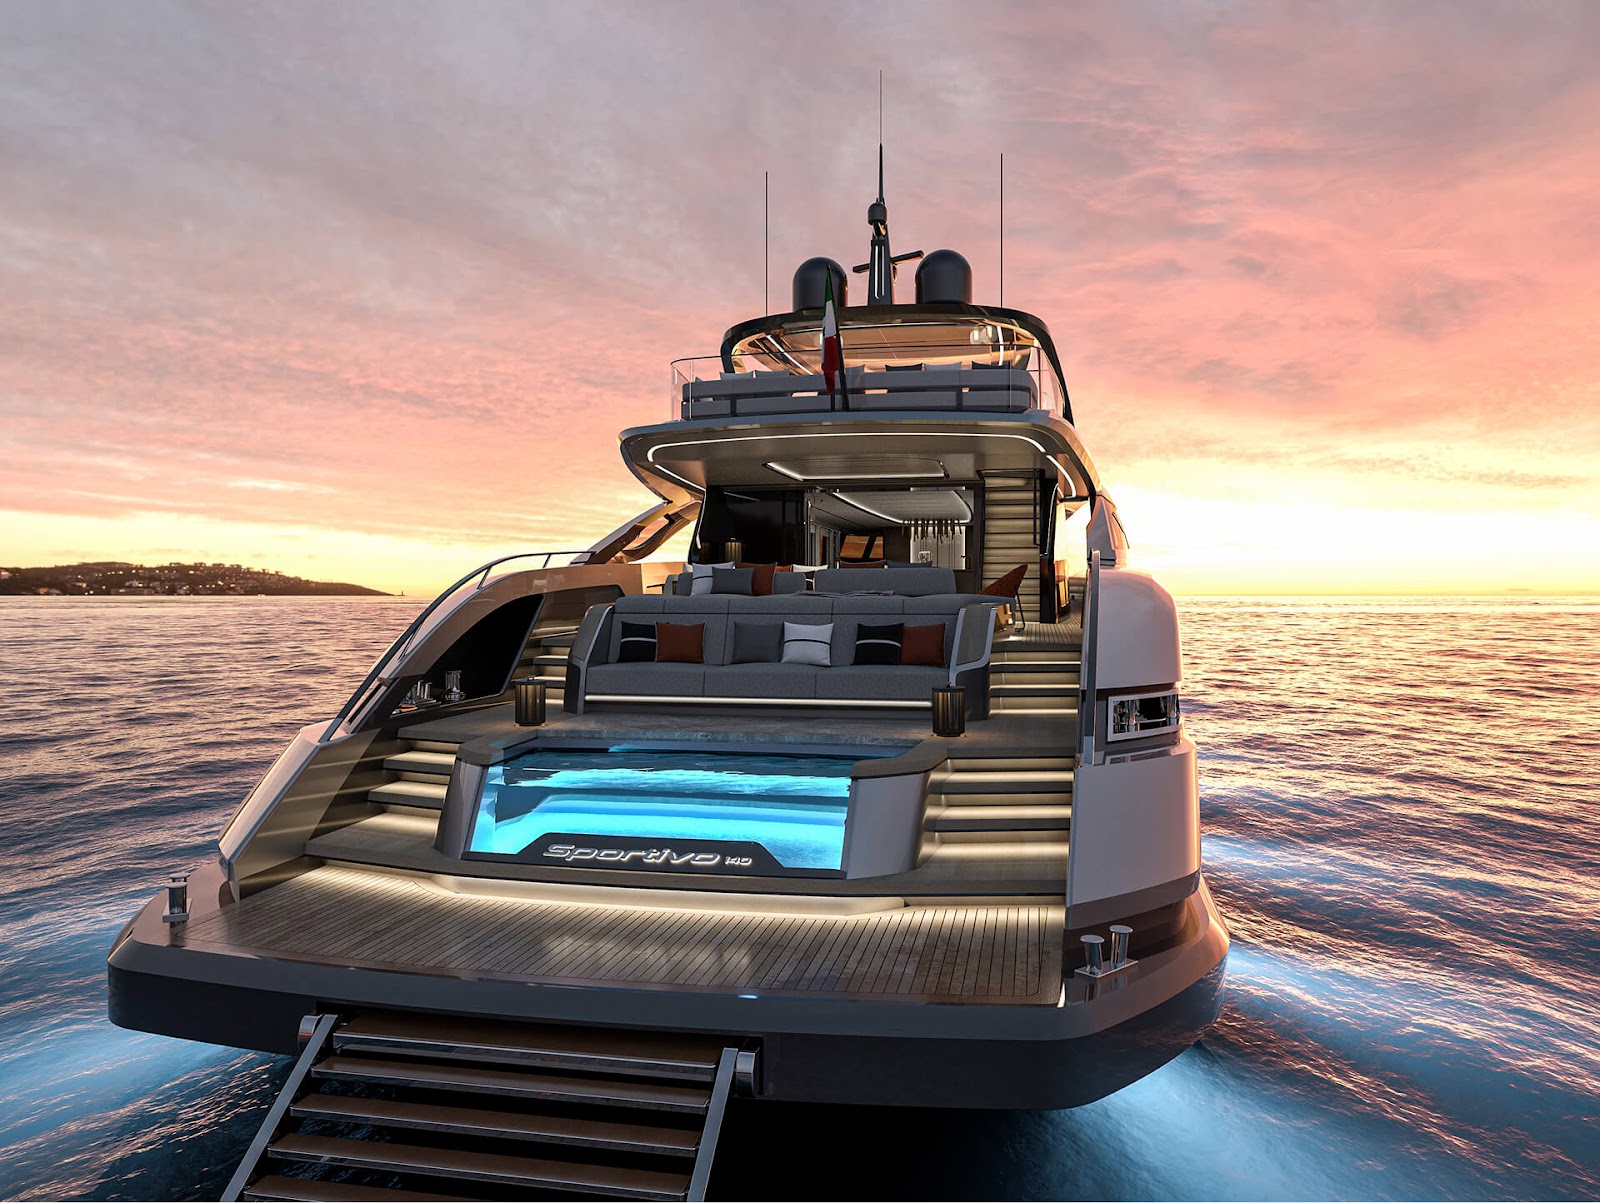
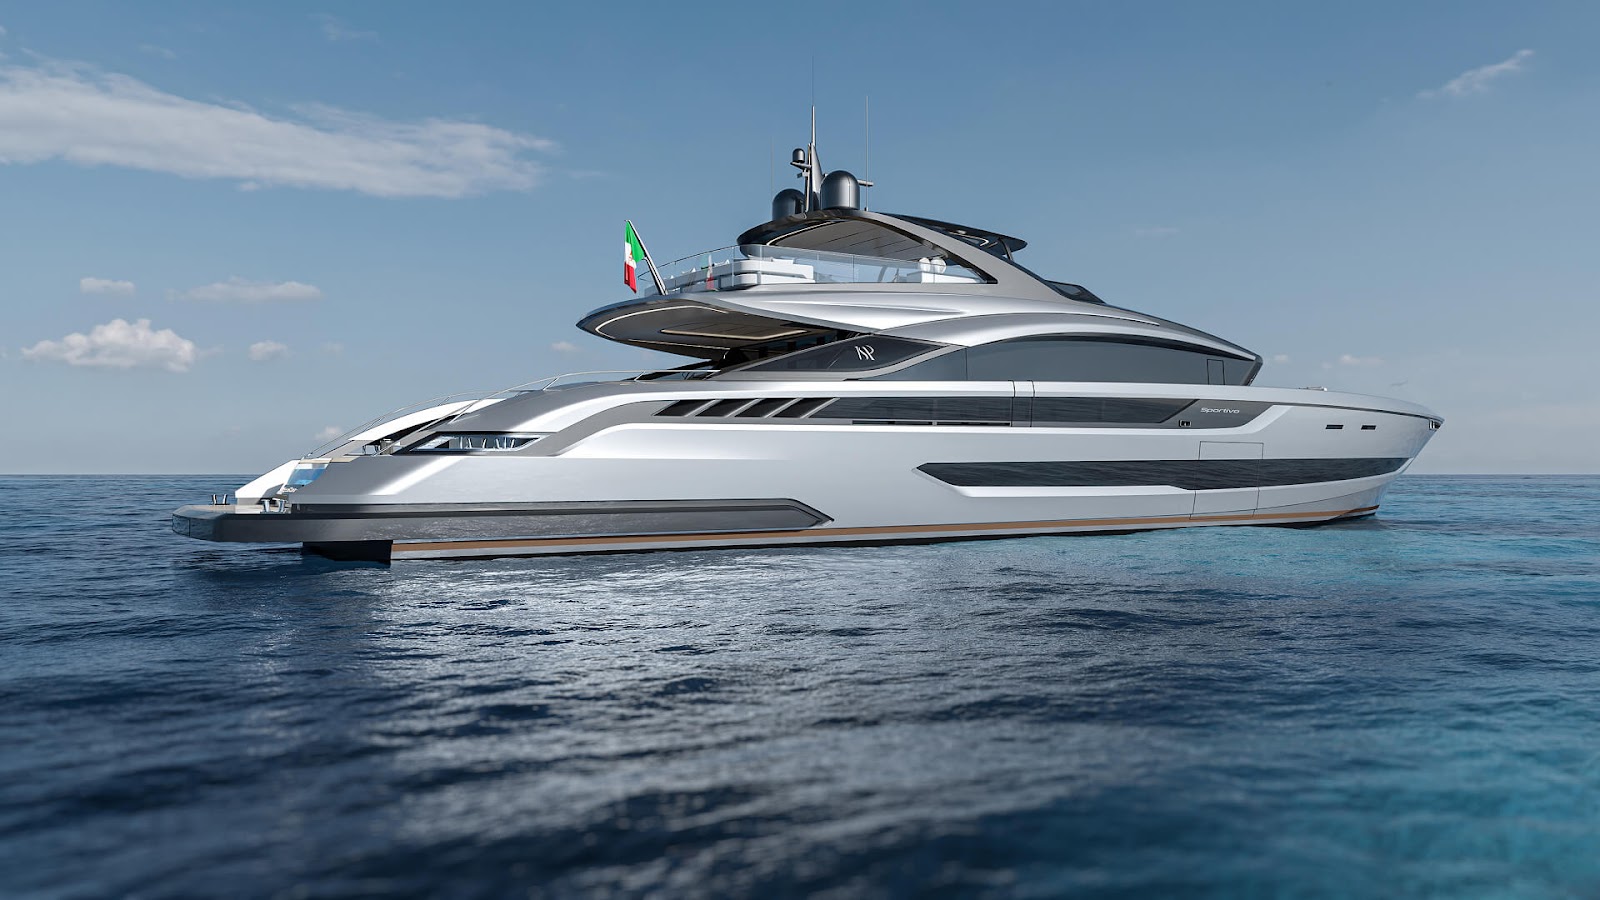
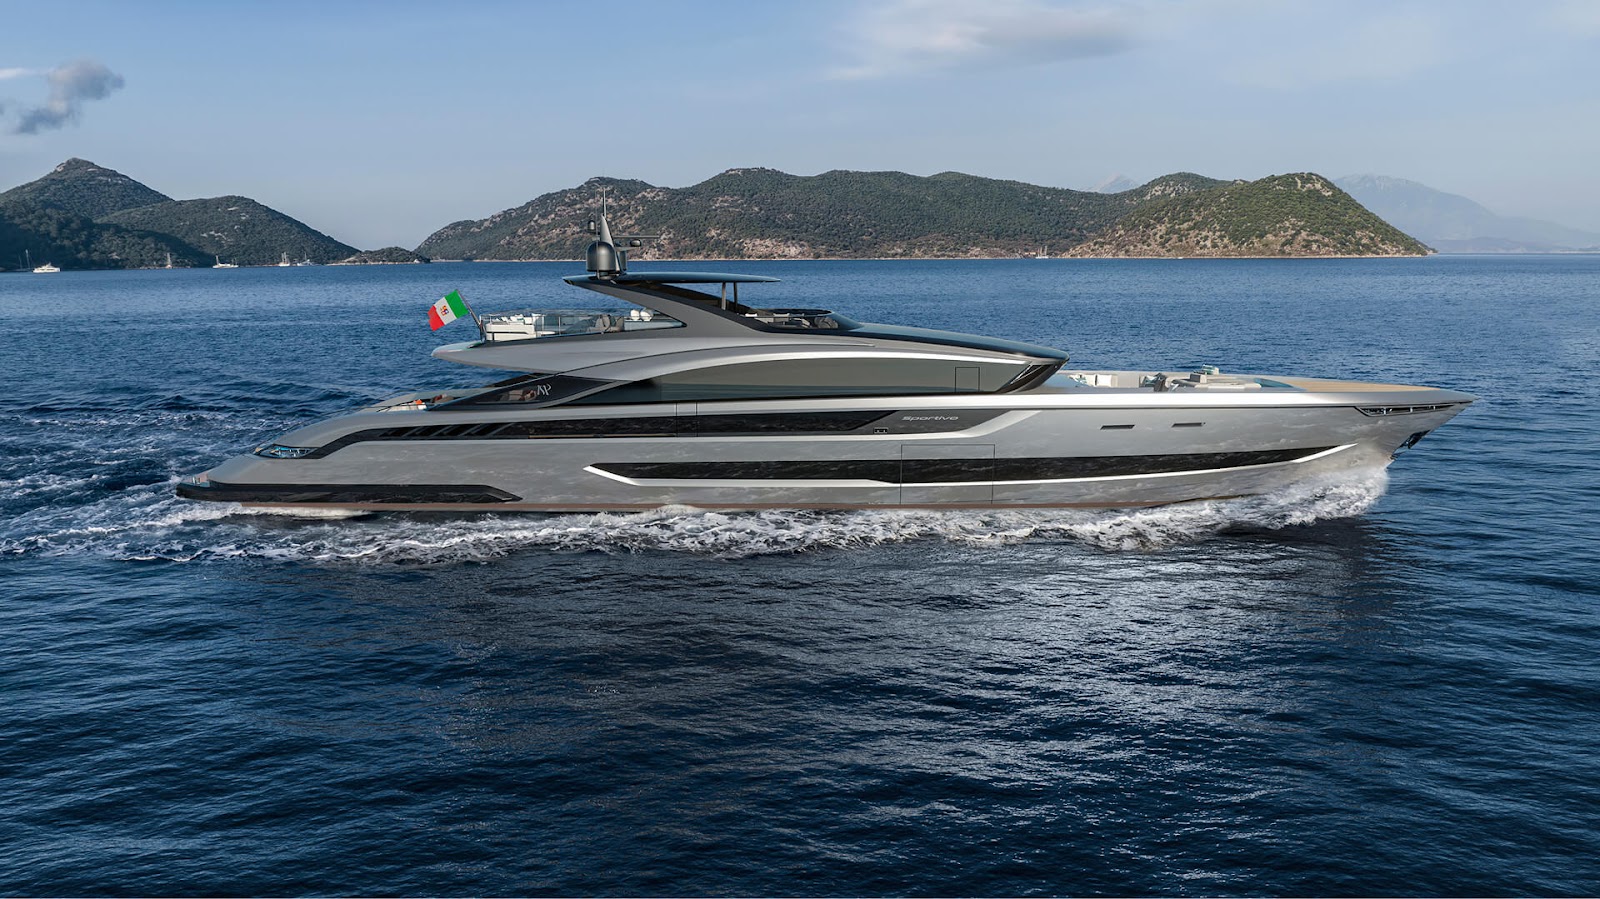
🛥️ ISA Sportiva 43.6M Superyacht
€25,000,000
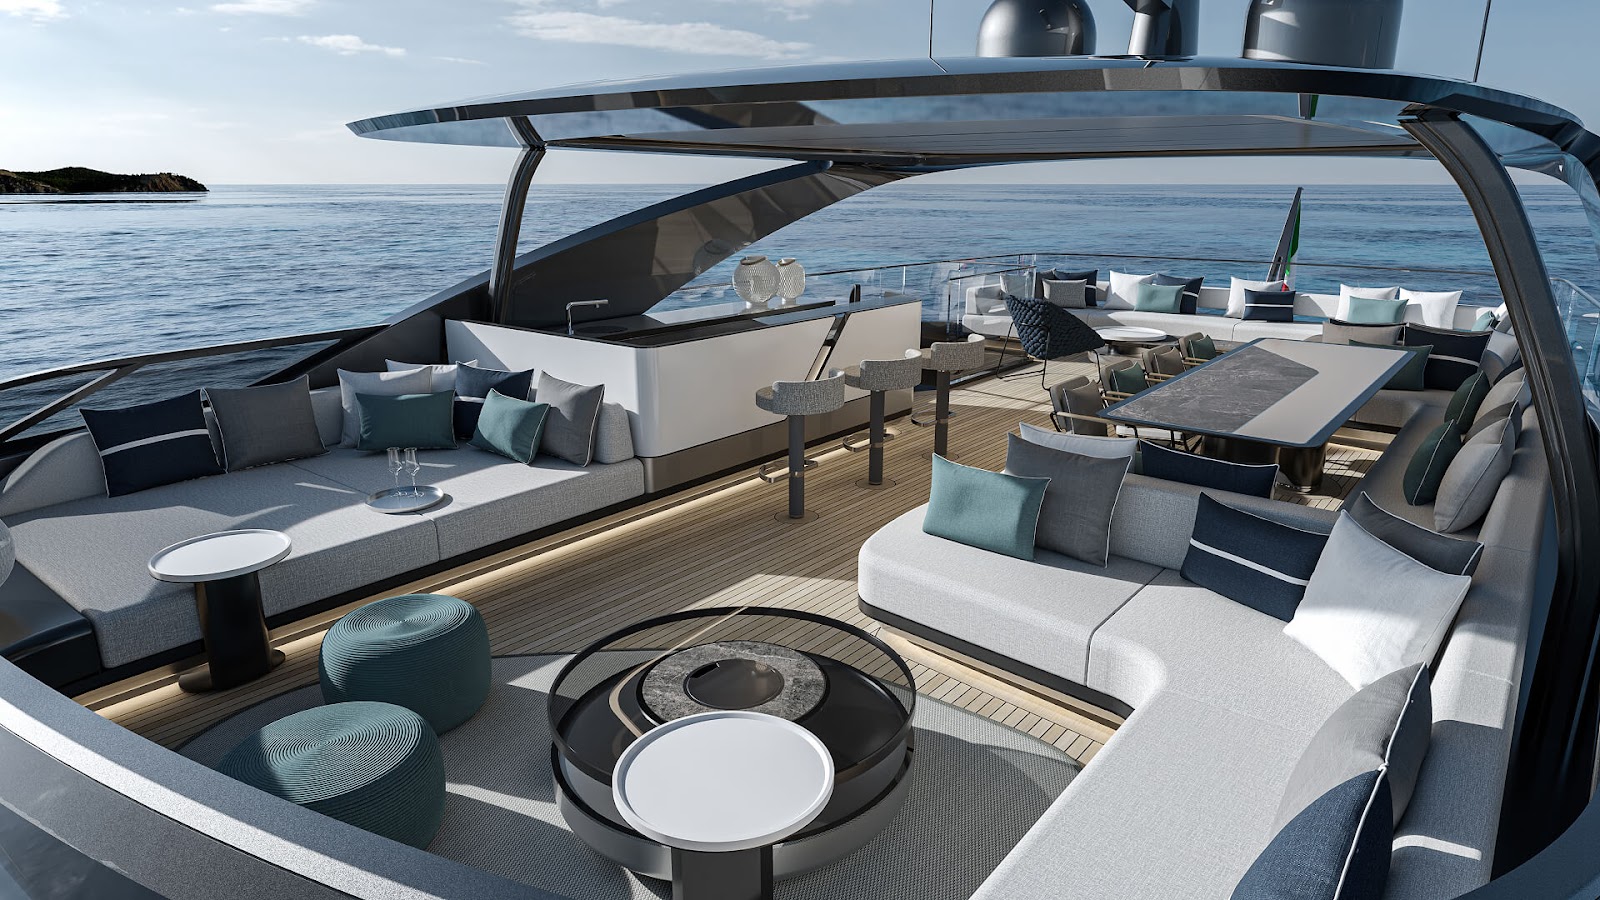
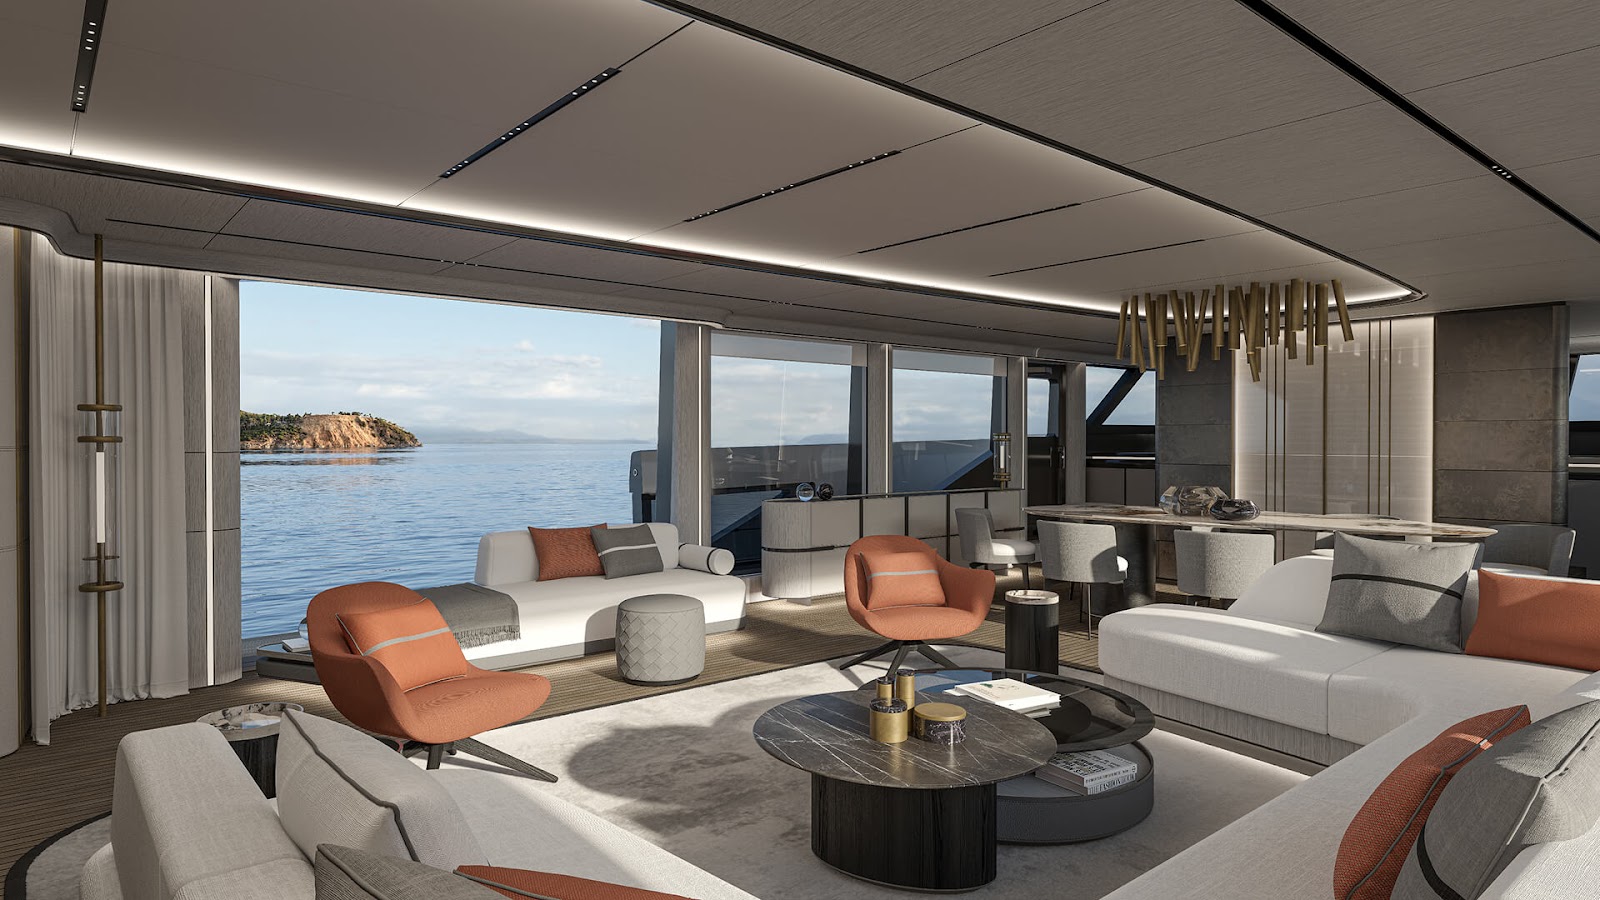
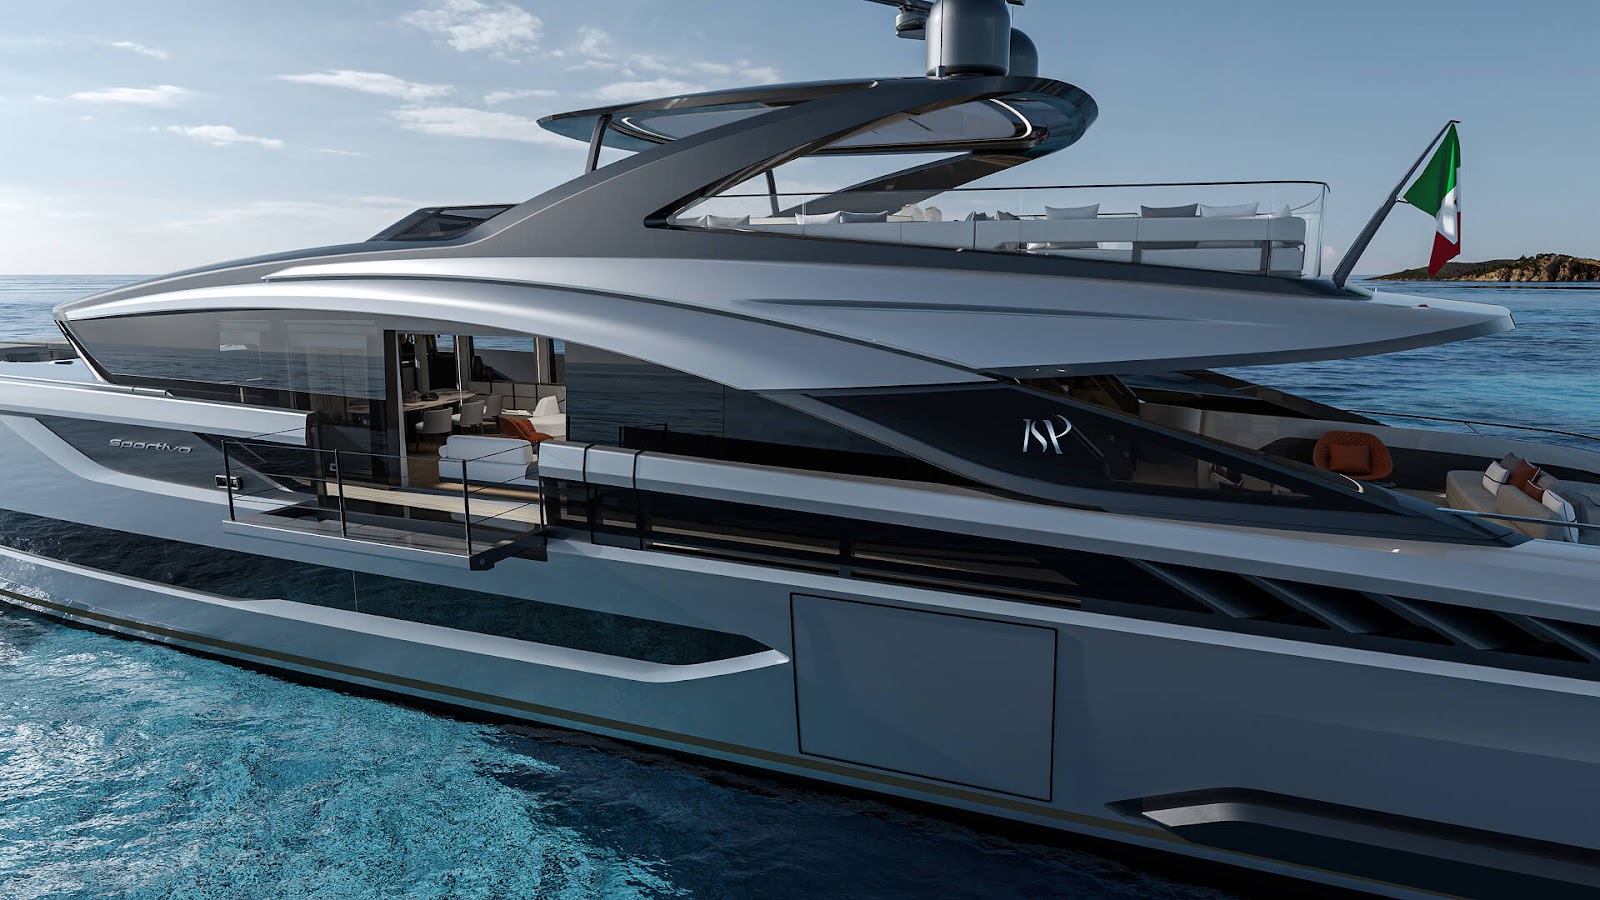
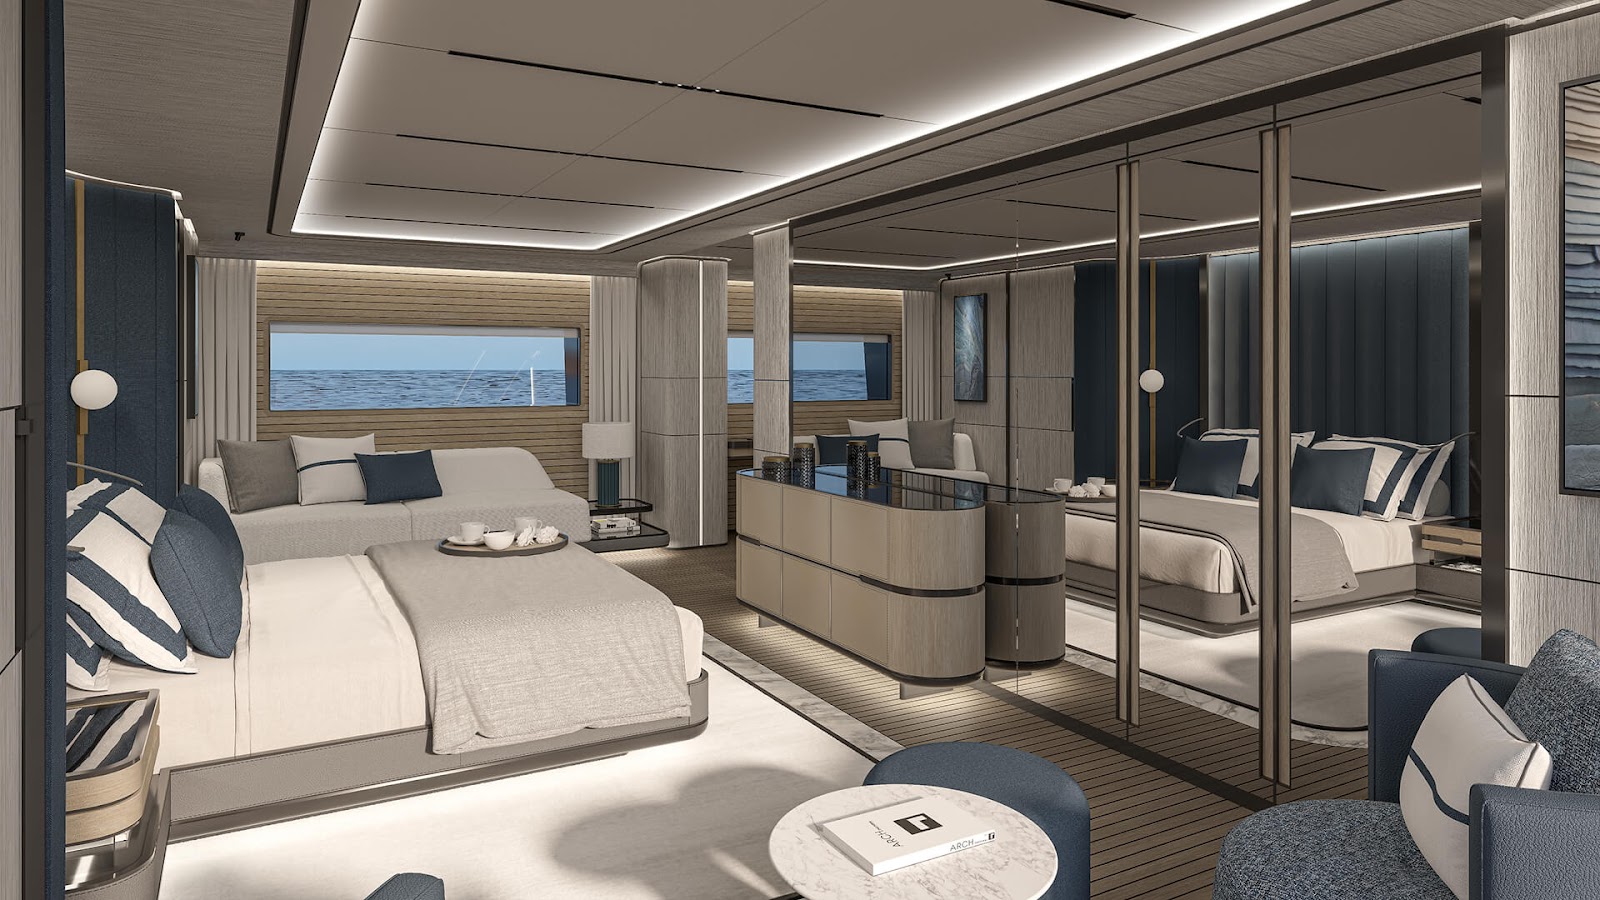
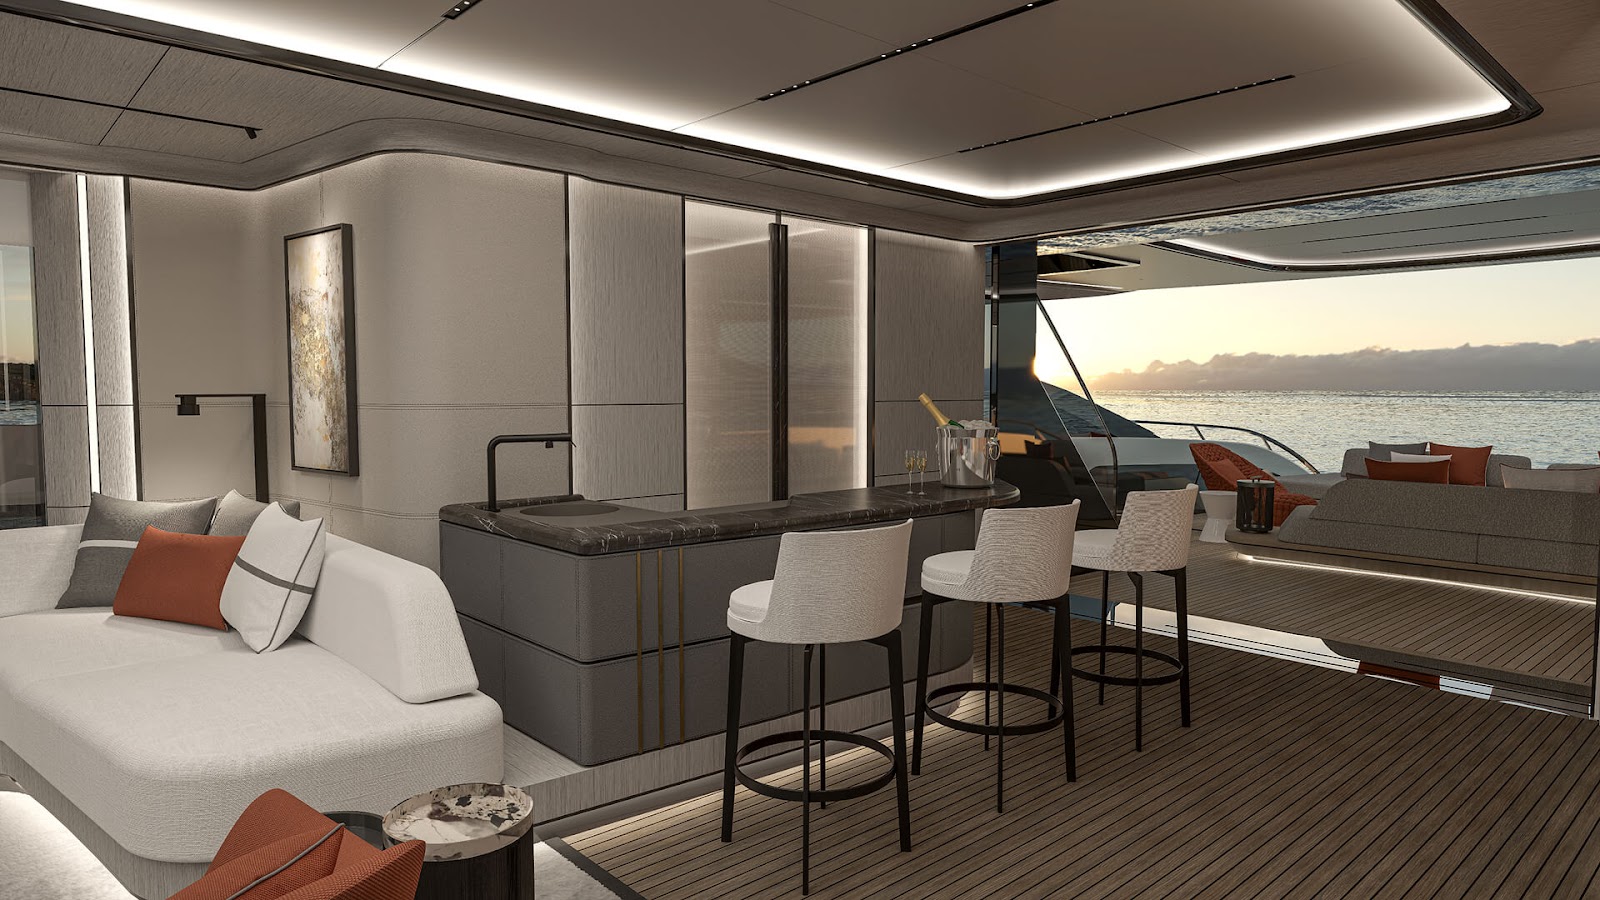
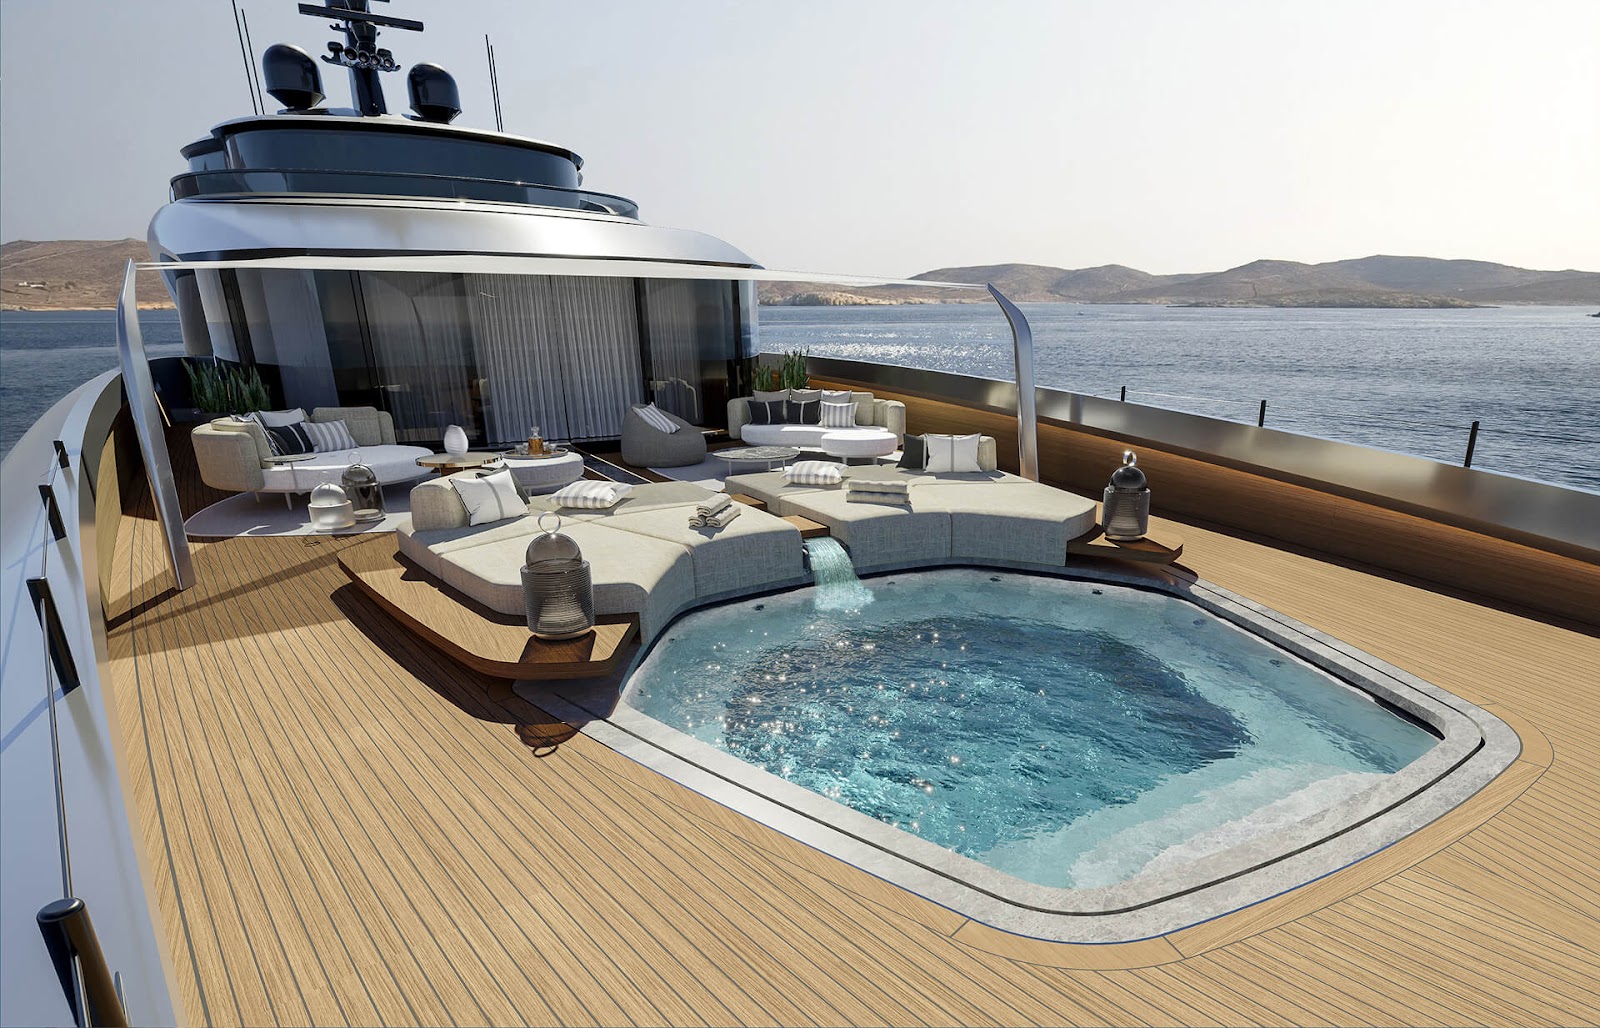
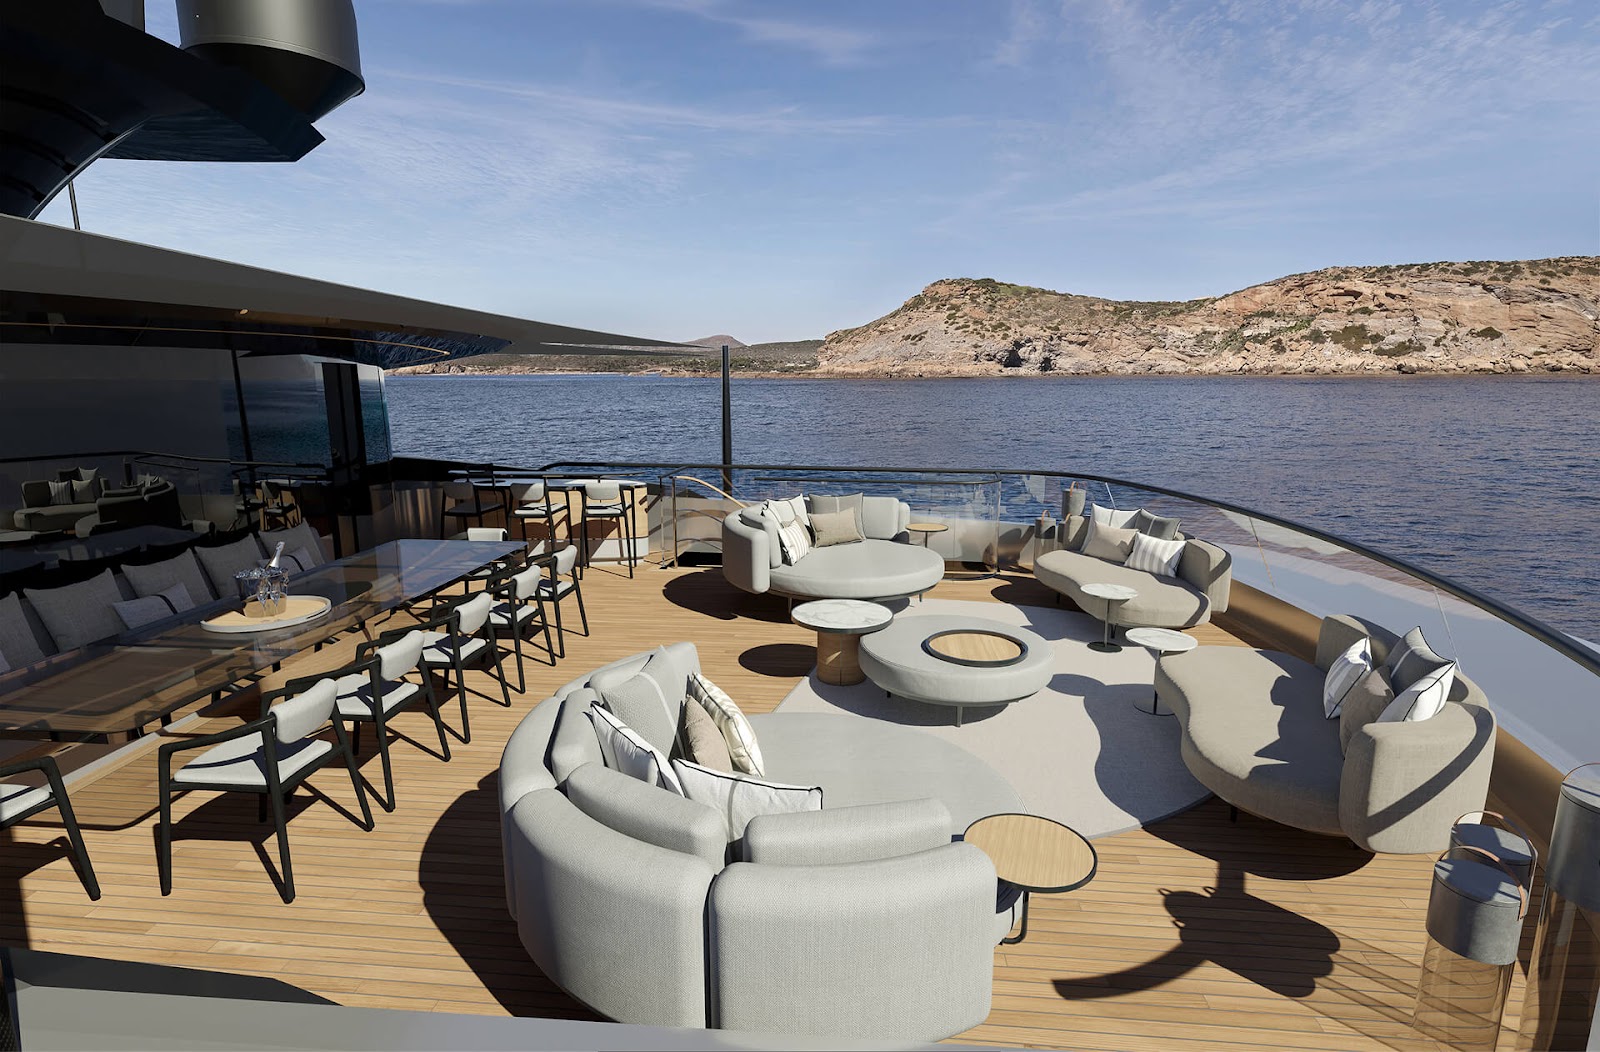
A masterpiece of Italian craftsmanship — a 43-metre sports yacht where the coupé lines of the automotive world meet the open sea. Designed by Marco Casali with a signature ISA arch connecting the decks. Five staterooms including a full-beam owner's suite, upper-deck saloon converting to private cinema, beach club with fold-down balcony, three sun-pad areas, and a glass-bottomed bow pool.
Twin MTU engines. Top speed 19 knots. Range 3,800 nautical miles — from the Balearics to the Bosphorus without stopping.
DELIVERY: MAY 2028
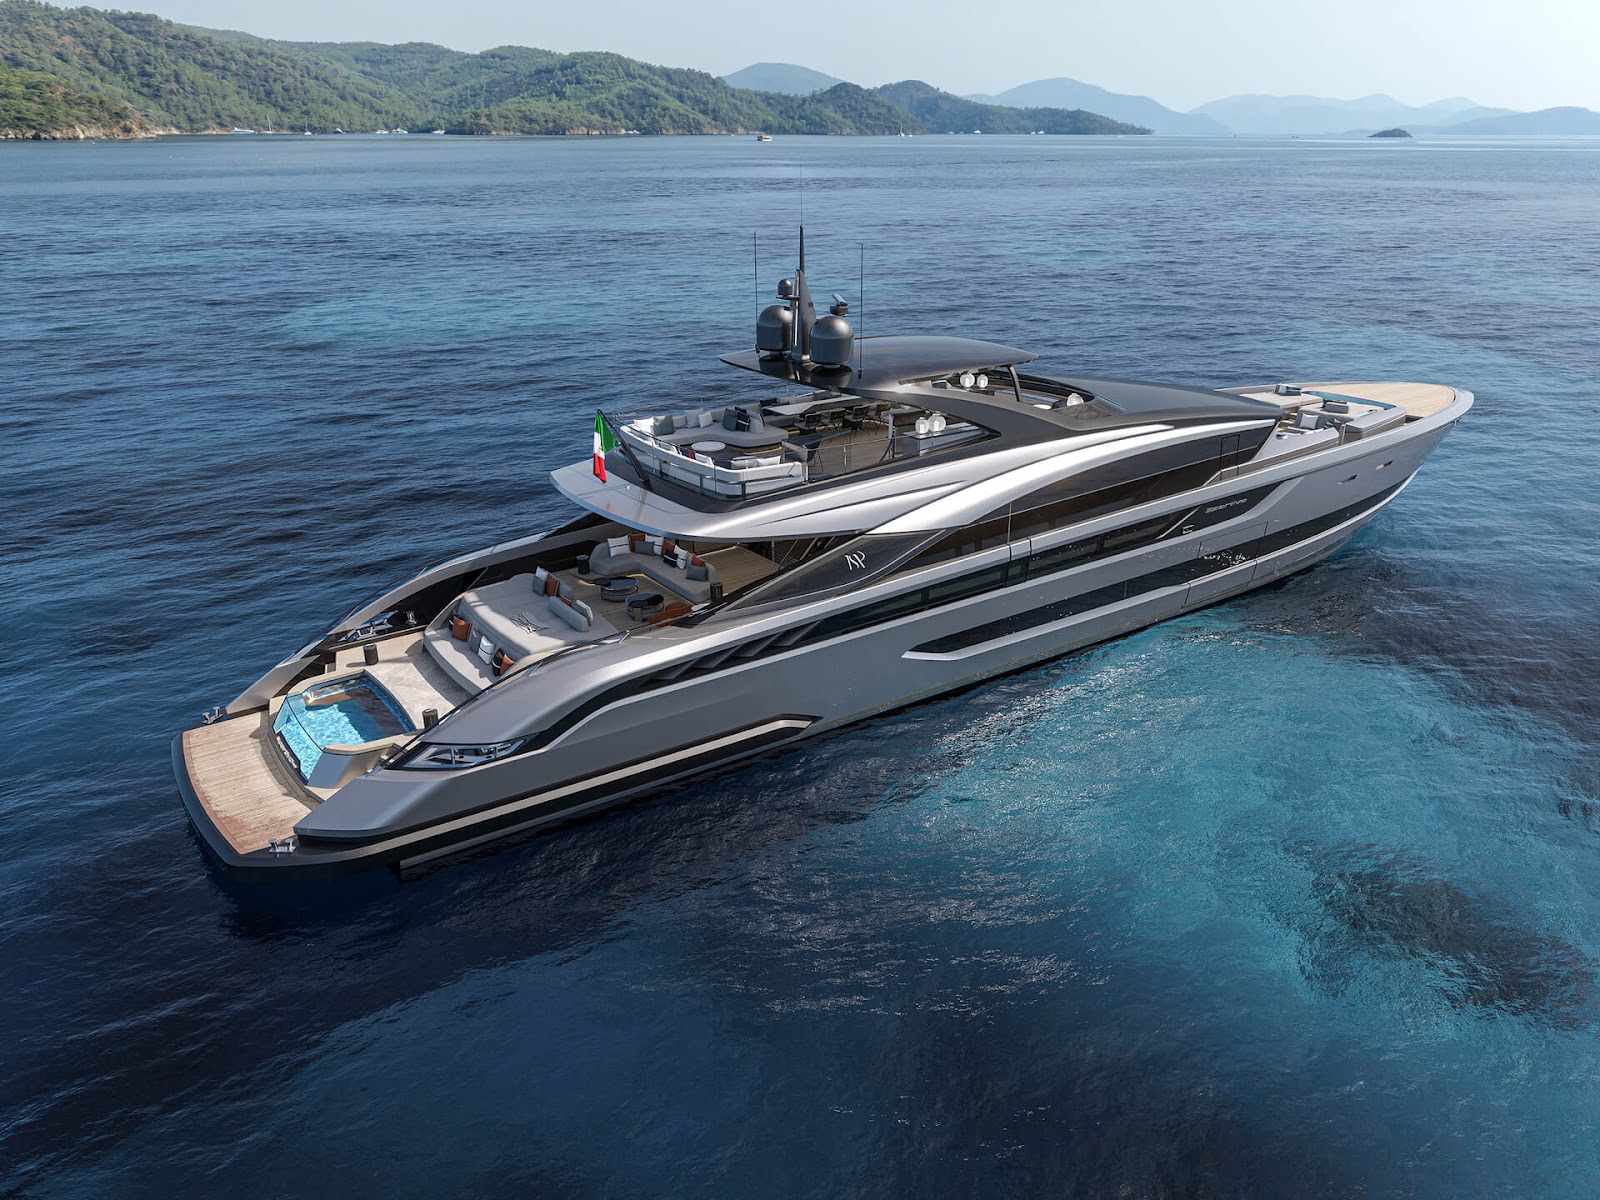
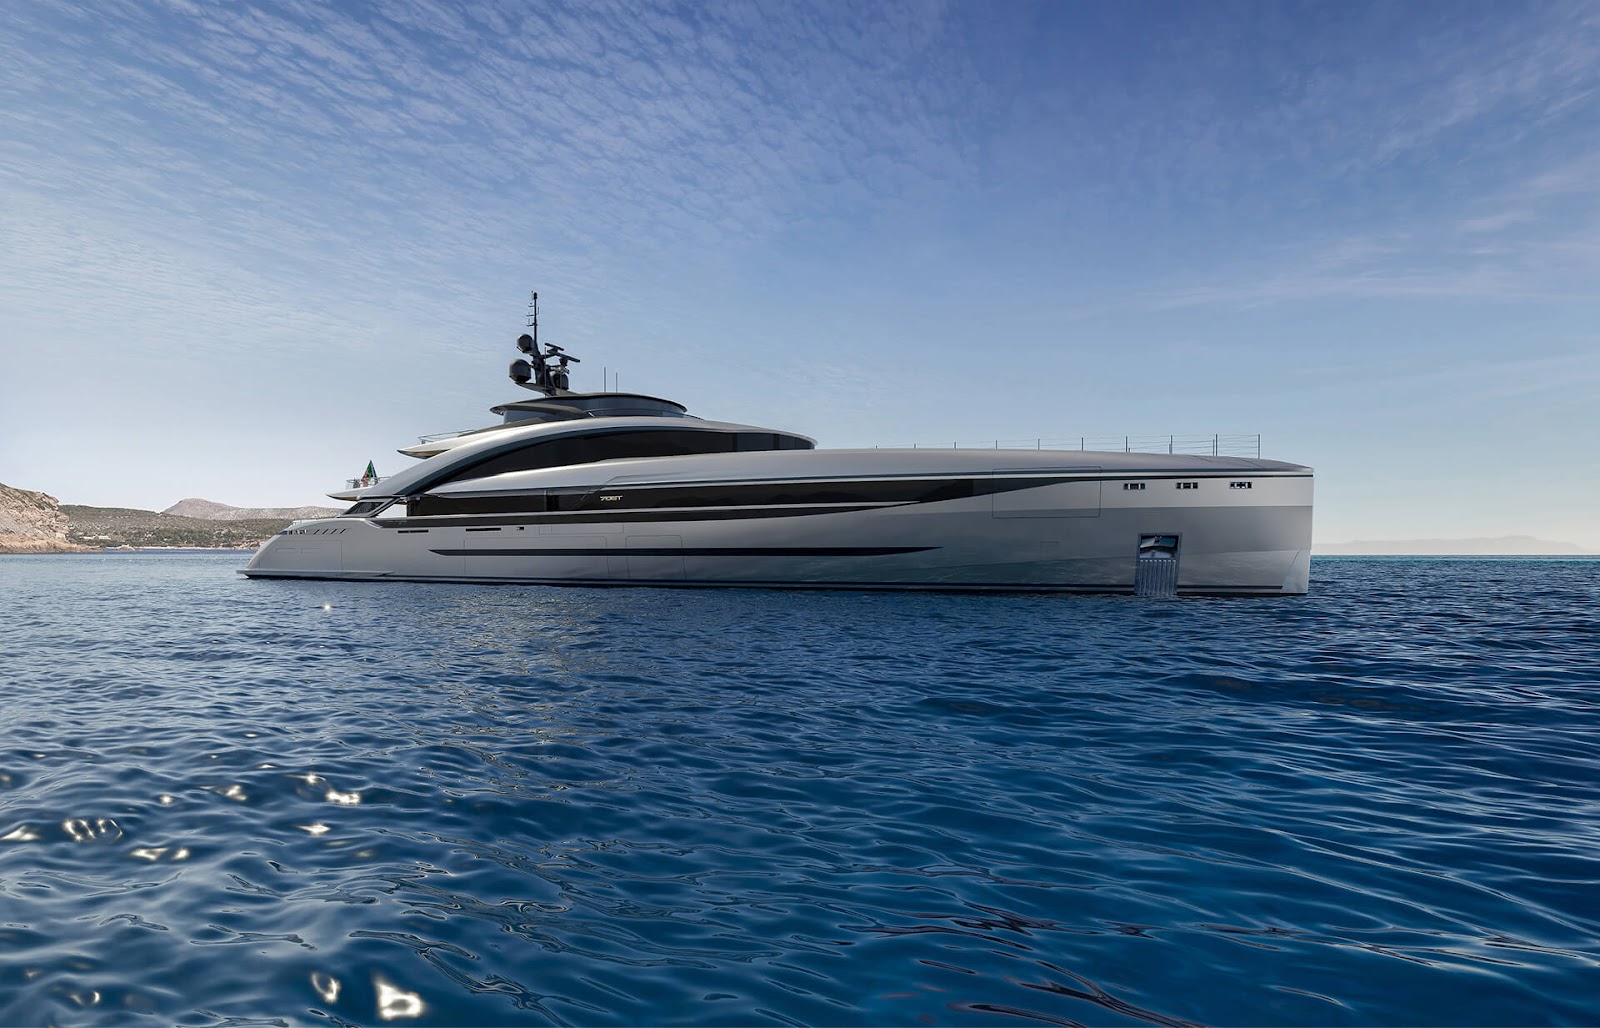
🚤 ISA Gran Turismo 70M Superyacht
€78,000,000
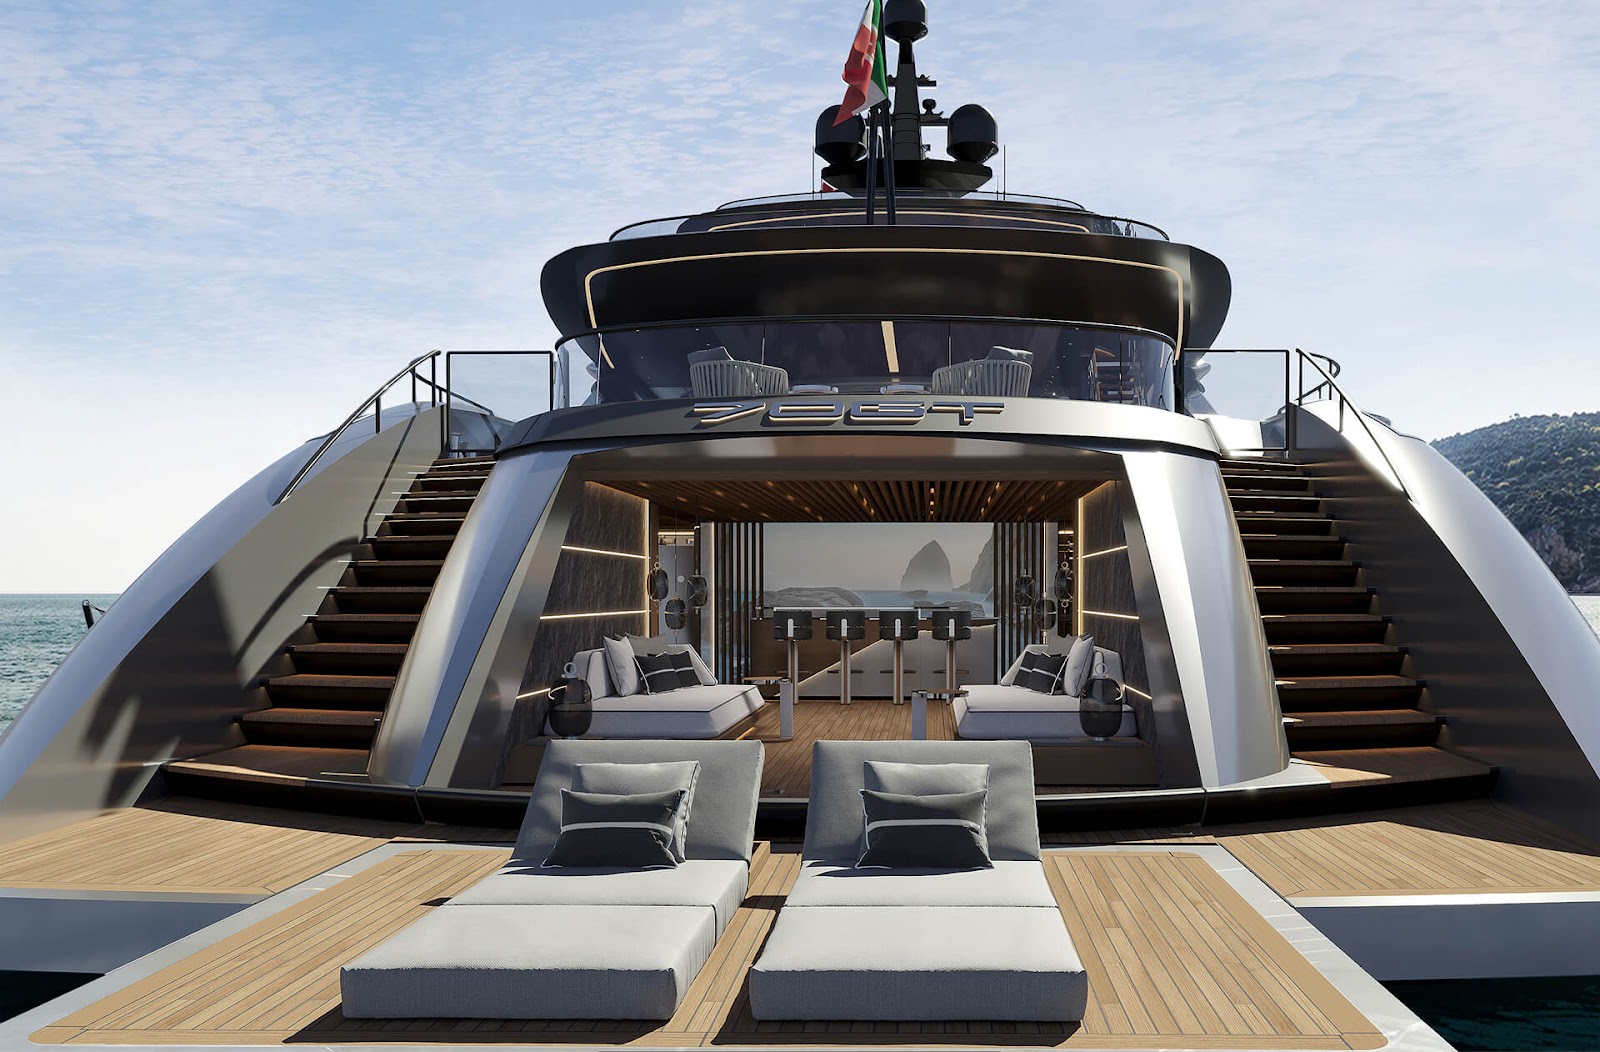
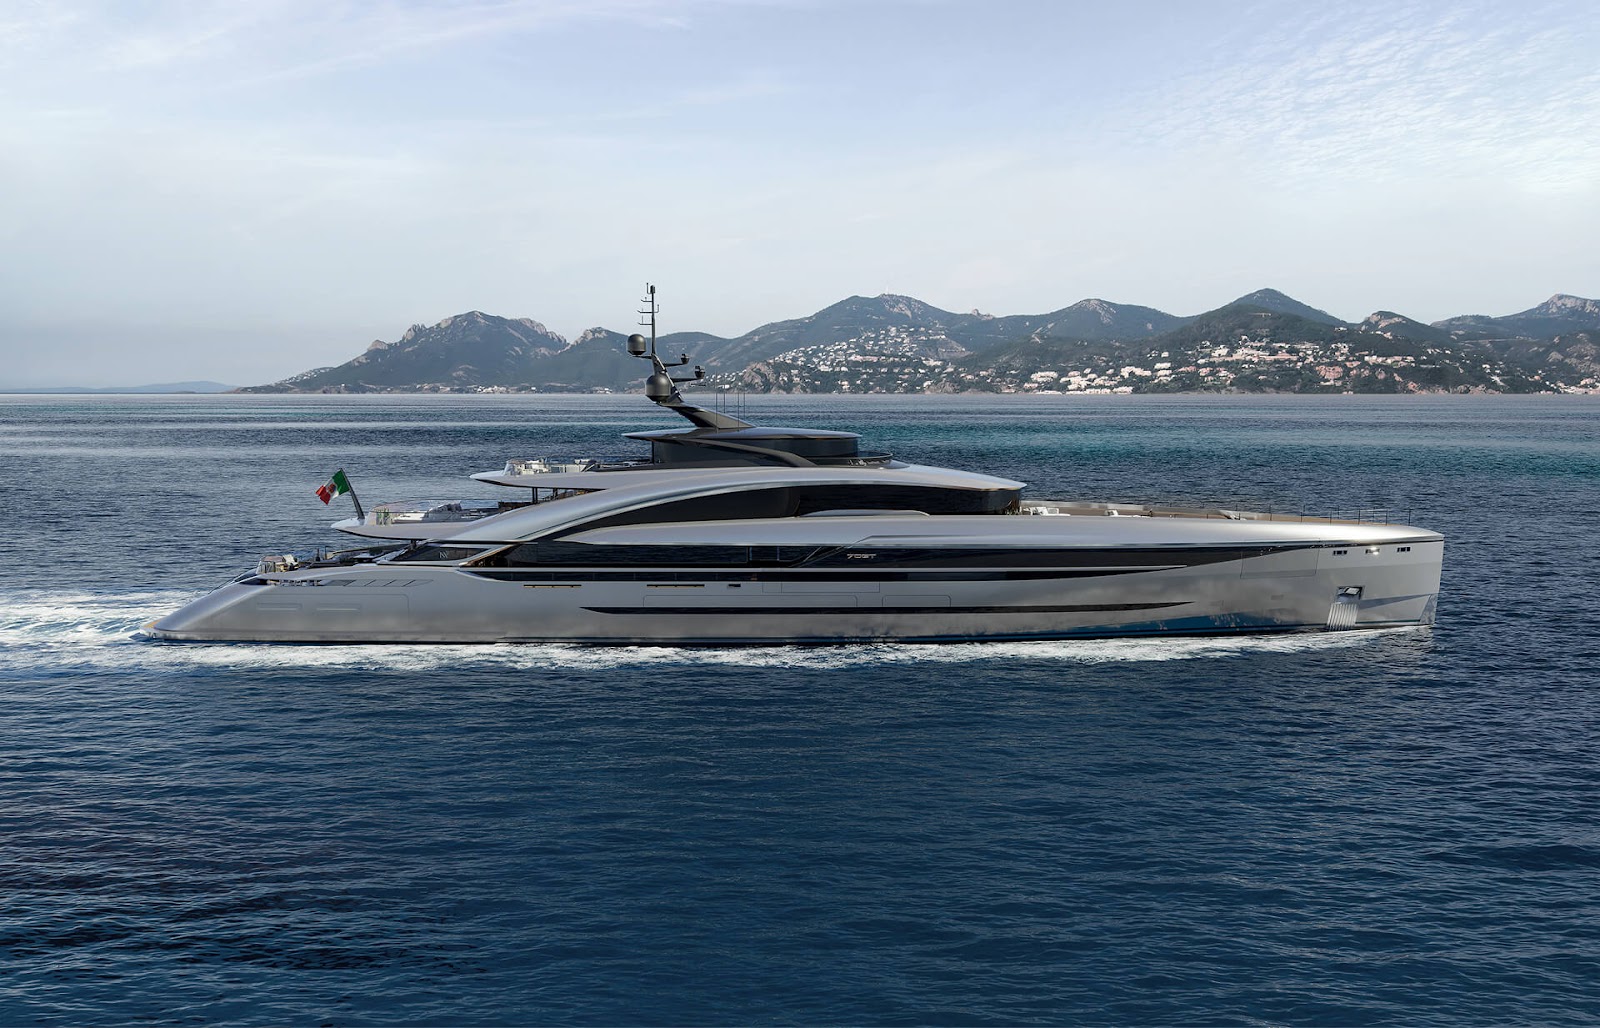
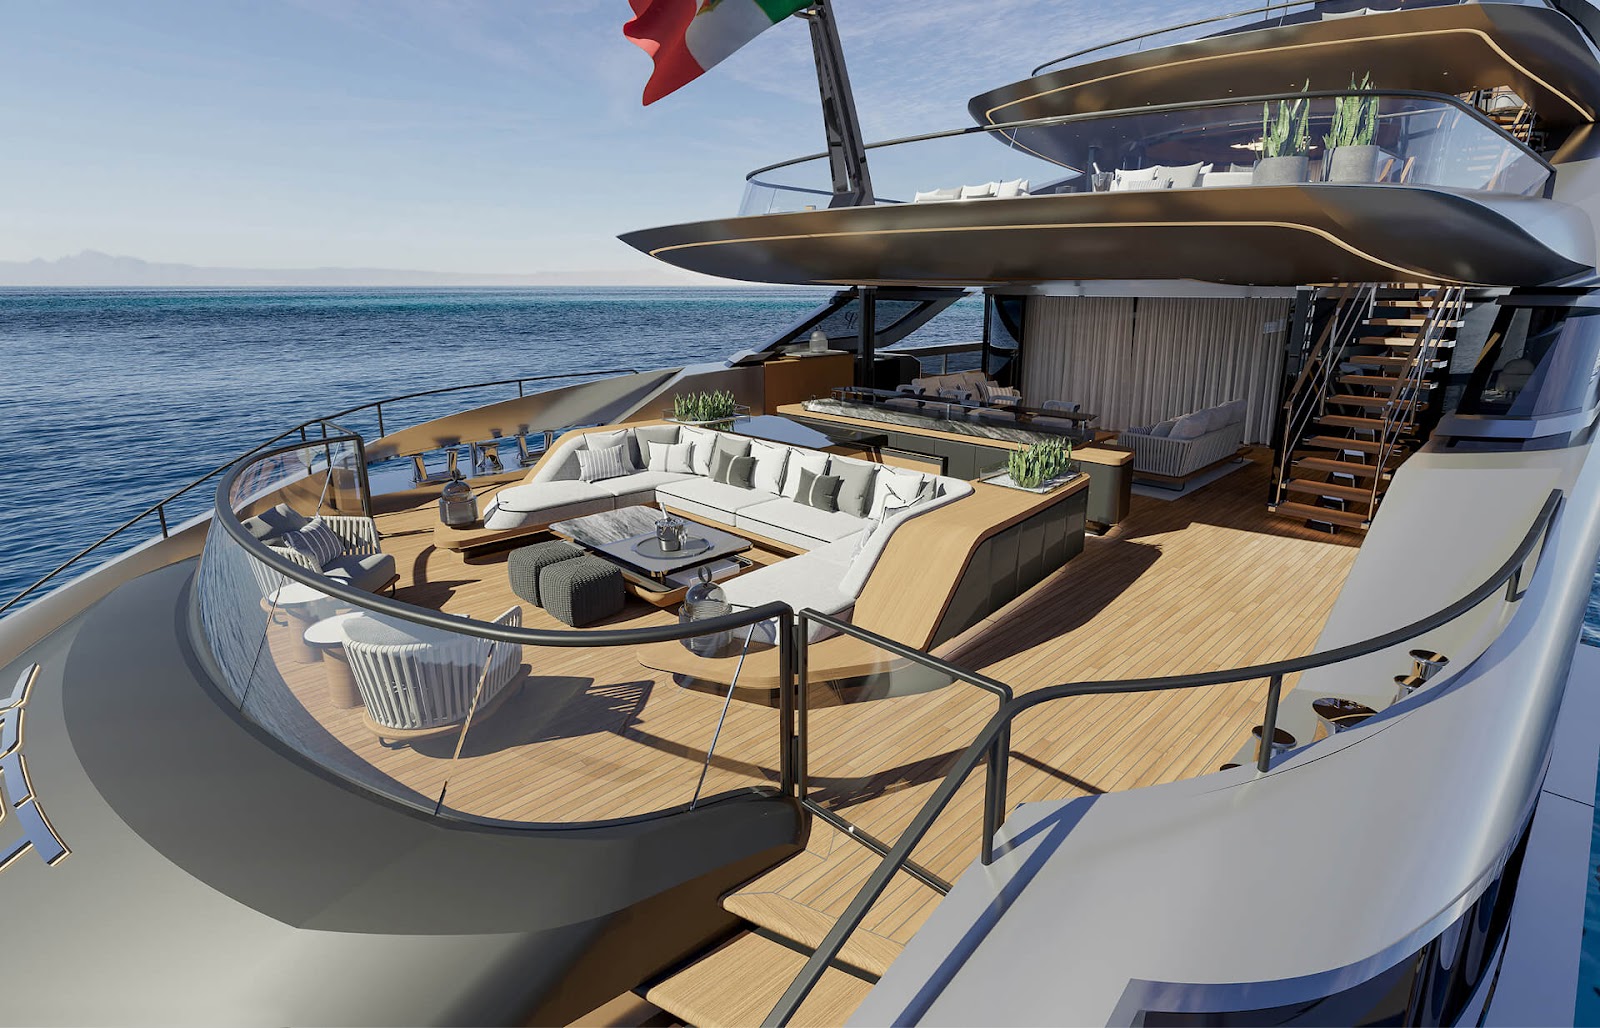
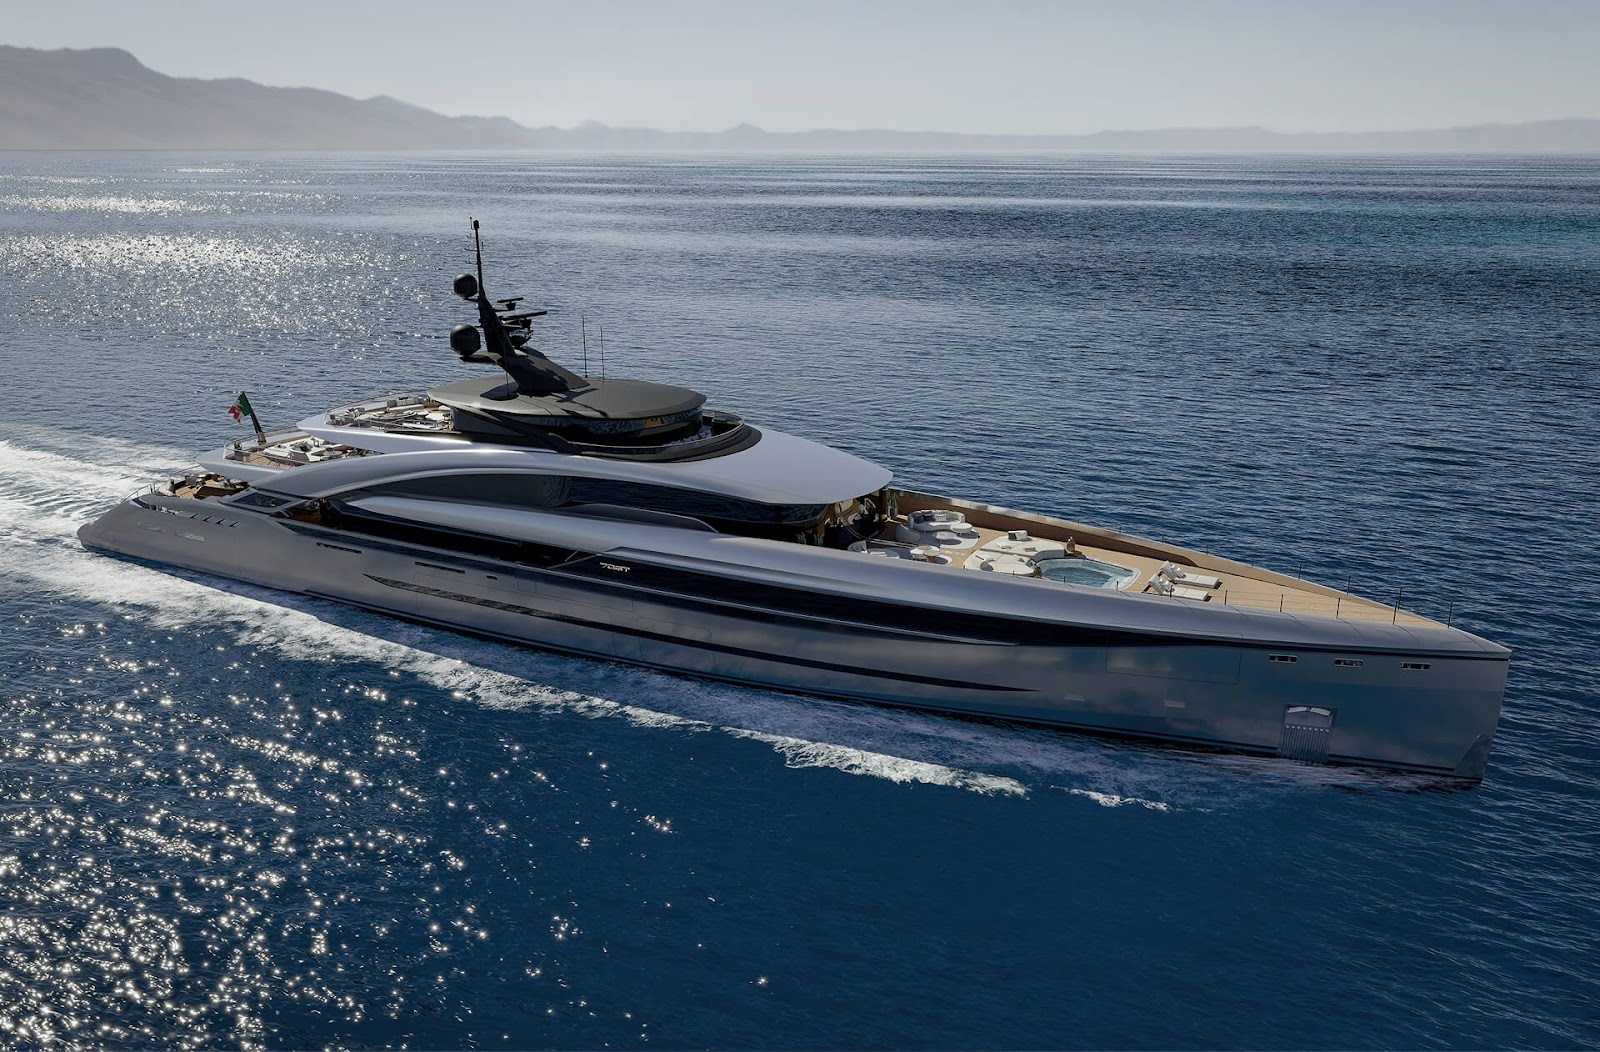
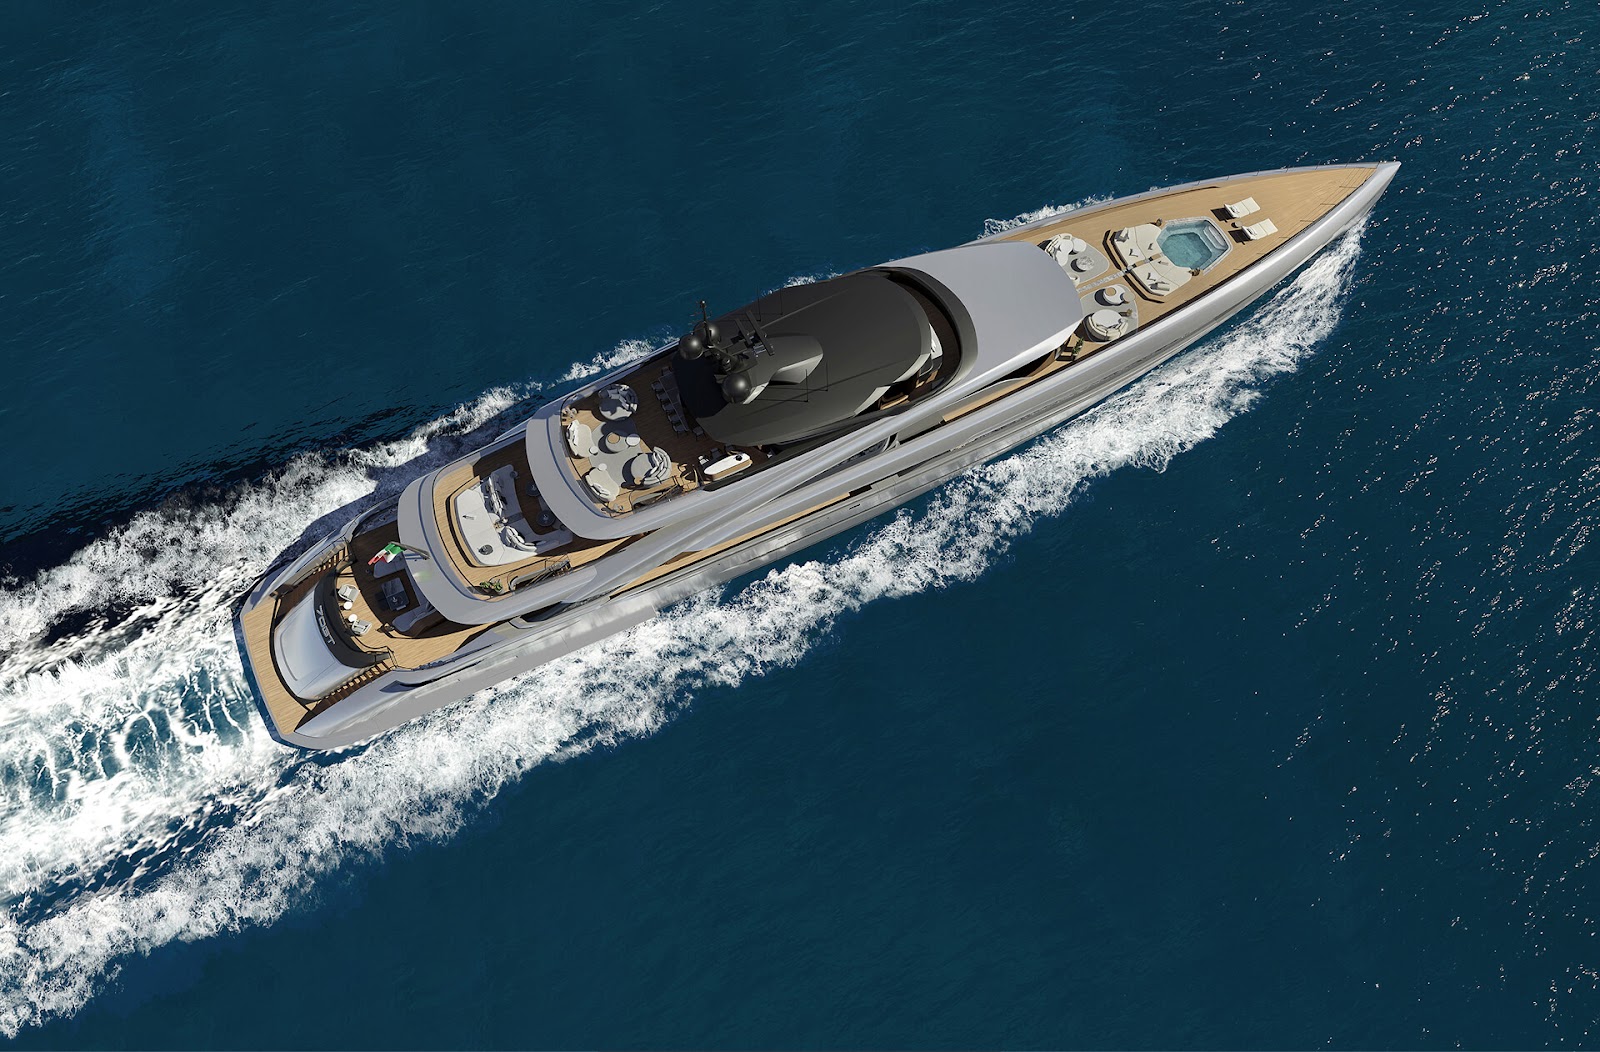
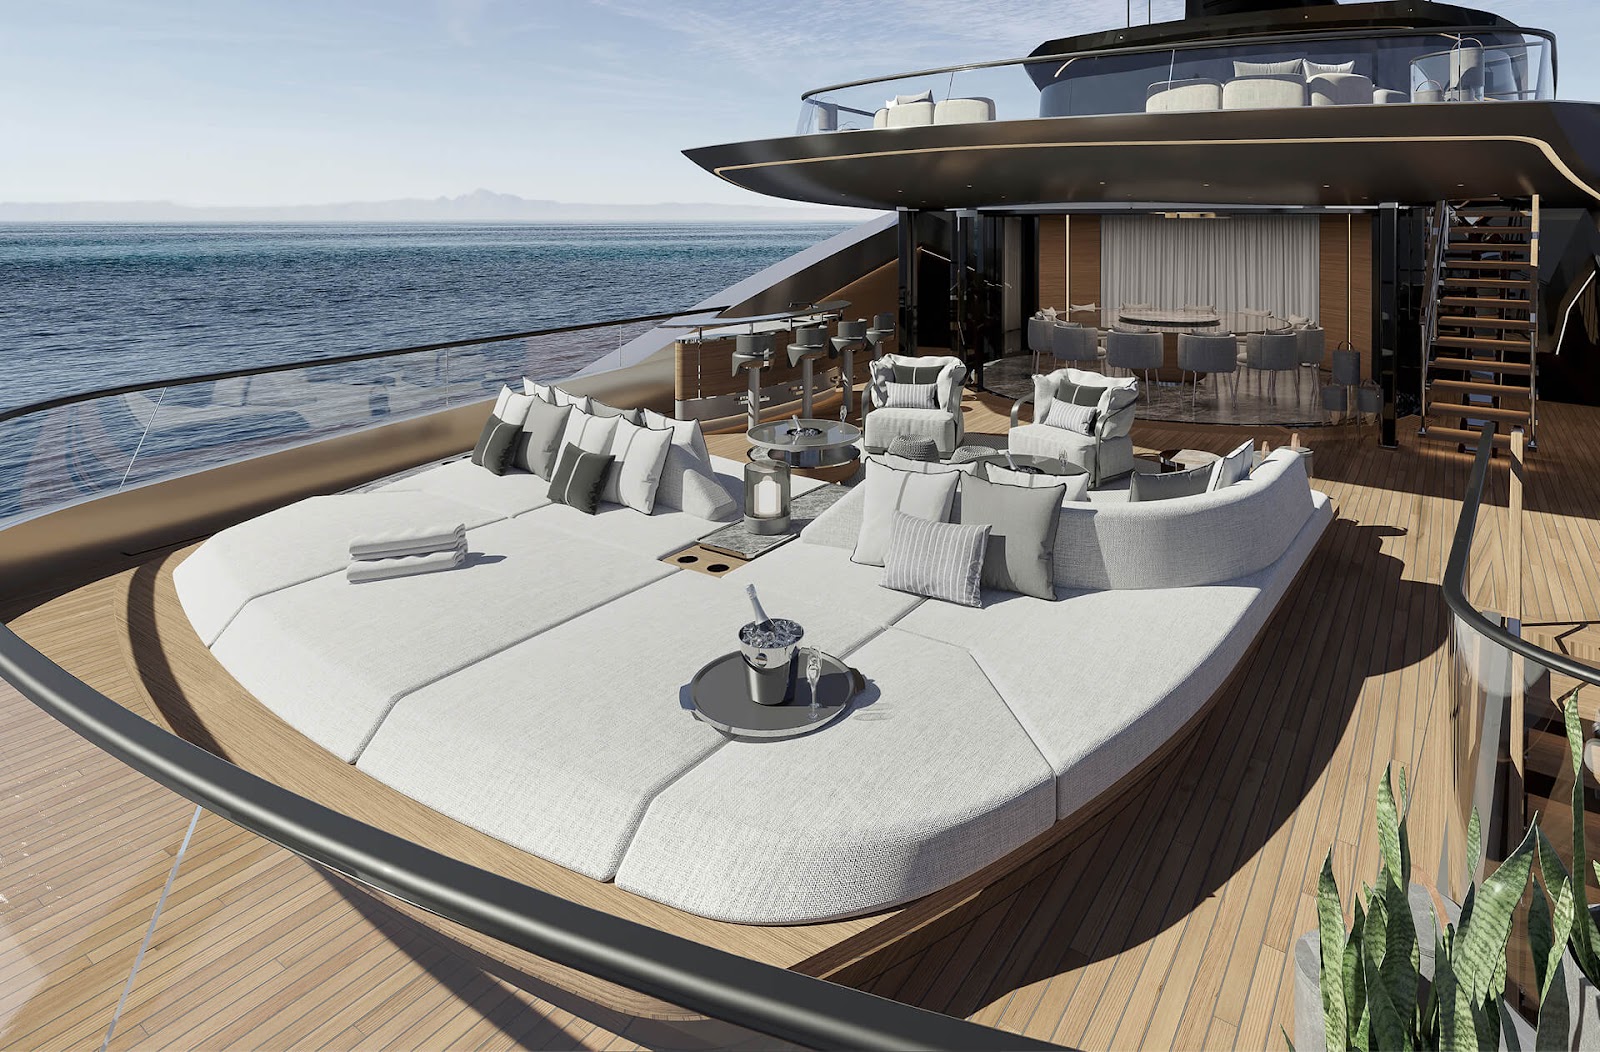
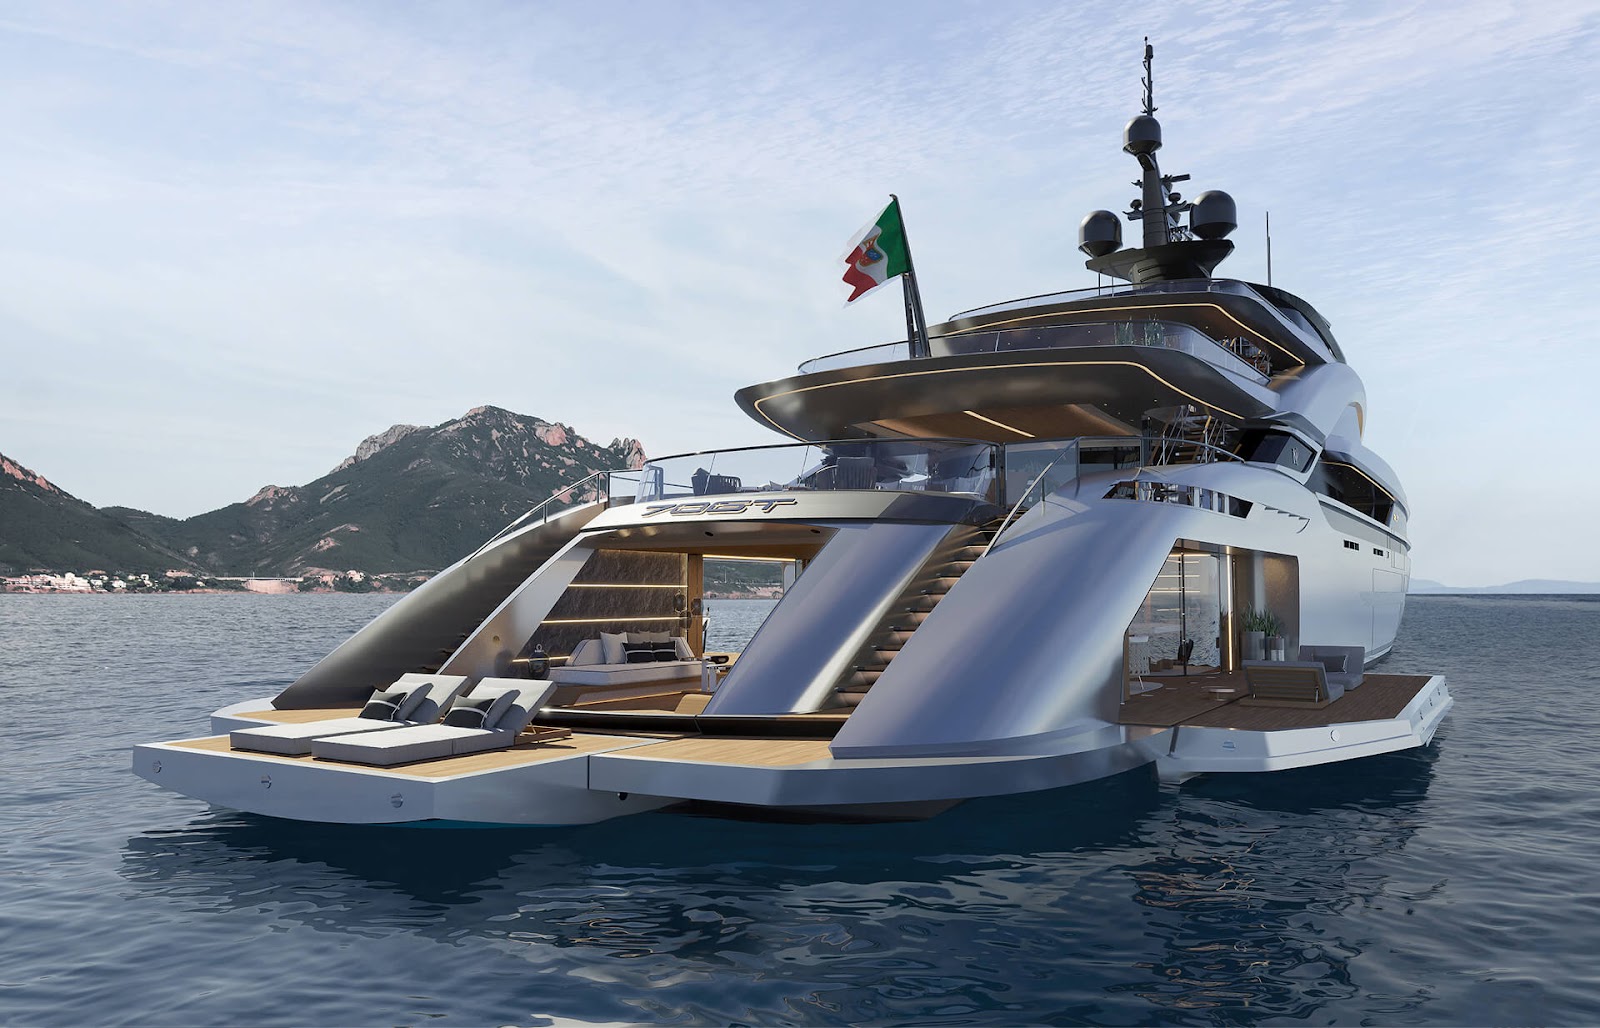
ISA Yachts' flagship Gran Turismo 70 — 70 metres of coupé-like elegance. Designed by Enrico Gobbi of Team for Design. Steel-grey hull with charcoal detailing and the signature ISA arch. The owner's "glasshouse" suite forward on the upper deck is framed by floor-to-ceiling windows. Five double guest cabins, beach club, spa, and three fold-out swim platforms.
Twin MTU engines. Top speed 17.5 knots. Range 5,500 nautical miles — the entire Mediterranean and beyond, without refuelling.
DELIVERY: Q2 2029
Usage Policies & Privileges
Reserved for Trust beneficiaries.
🏨 Villa Las Tronas
Access 60 days per year — off-season or summer
Eligibility Immediate family & registered partners only
Inclusions Full accommodation, gourmet meals, unlimited spa, business class flights, £1,000 shopping allowance per person per day
Notice Required Minimum 3 months
Cost Completely free under Trust rights
⚓ ISA Superyachts
Access 60 days per year combined across both vessels, taken as whole weeks or as individual days
Eligibility Immediate family & registered partners only
Inclusions Full crew, all meals & premium wines, fuel, docking fees, business class flights, £1,000 shopping allowance per person per day
Deposit Refundable security deposit of €100,000 per week, calculated pro rata for shorter stays
Notice Required Minimum 3 months
Cost Completely free under Trust rights
📆 How Dates Are Allocated
School holidays and the summer weeks will be wanted by more than one household. Rather than leave that to whoever asks first or argues longest, the trustee allocates.
Requests Submitted to the trustee by 31 October for the following year
Peak periods July, August, Christmas and Easter are allocated by rotation. A household that receives a peak period goes to the back of the queue for that period the following year
Households with school-age children take priority for school holidays over those without
Everything else First come, first served, with the three months' notice
Sharing Two households may take a period together by agreement, and it counts once against each rotation
Unclaimed dates Released to any beneficiary at four weeks' notice
The trustee's allocation is final. That is not bureaucracy for its own sake — it is so that no one in this family ever has to negotiate with a cousin over a week in August.
🎟️ Bringing Guests Aboard
Neither vessel is available for charter to anyone outside the family. What is available is a berth alongside you. A beneficiary may bring friends on a trip they are already taking, and those guests contribute at half the published per-person rate — the figure a broker would quote for the same cabin on the same water.
The published per-person rate is the vessel's standard weekly price divided by the number of guests she carries. The daily figure is one fifth of the weekly, because a short stay costs proportionally more to provision and crew. Deposits are per person, calculated pro rata against the length of the stay, and returned in full within fourteen days of disembarkation.
43.6M · Sports Yacht · 10 guests
ISA Sportiva
€1,850/person/day
Published rate: €3,700 per person per day
50% BELOW PUBLISHED
Or €9,250 per person per week · minimum 3 days · deposit €5,000 per person per week, pro rata
Agile, sleek, and built for those who value speed and style. The Aegean, the Riviera, the Balearics — in a sports yacht that turns heads in every port.
70M · Flagship Superyacht · 12 guests
ISA Gran Turismo
€4,160/person/day
Published rate: €8,320 per person per day
50% BELOW PUBLISHED
Or €20,800 per person per week · minimum 3 days · deposit €10,000 per person per week, pro rata
The pinnacle of maritime grandeur. 70 metres, twelve guests, a glasshouse owner's suite, beach club, spa, and a range that reaches the Caribbean.
Guest berths do not come out of your sixty days, and a guest may never travel without the beneficiary who invited them. Cabins are subject to availability, and the trustee handles the arrangement.
Why Guests Contribute
The house rules, briefly.
Beneficiaries and their immediate families use the villa and the vessels at no cost. Friends you bring along contribute at half the published per-person rate. That is not a judgement on anyone — it is simply how a vessel of this kind stays properly crewed, provisioned and insured without the Trust quietly subsidising a widening circle of guests.
There is one rate and no second one. Nobody need work out where they sit, and nobody need ask me for a better number — the trustee administers it, and has no authority to vary it. That is deliberate: a concession granted once becomes a precedent argued over for twenty years.
Acceptance Is Not in Question
You cannot decline. You can only leave it untouched.
There is no opt-out clause in this Trust, and that is deliberate. All ten are named in the deed from the day it is executed, and every child born into the family afterwards is added automatically. Nobody is asked to accept, because nobody is being offered a choice about belonging. You are in. The only decision left to you is a much smaller one: whether, and when, you draw.
I have removed the option to walk away because I can imagine one of you feeling that the dignified thing to do is to refuse. I understand that instinct, and I would ask you to look at it honestly before acting on it. Turning down provision of this scale is not a principled act — it is a decision whose weight falls almost entirely on people who never got a vote: a spouse not yet met, children not yet born, and a version of yourself at sixty who may see the matter very differently. Pride is a poor trustee. I have chosen not to hand it the keys.
If the hesitation concerns where the money came from, let me deal with that plainly, because it is the one objection that deserves a straight answer rather than a persuasive one. My past is not hidden from any of you. I was convicted, I went to prison three times, and I paid the price the law demanded and a good deal more besides. That chapter is closed, and it is not the source of what sits in this Trust. Every pound held here was earned lawfully, declared and taxed in full, and taken through source-of-funds and anti-money-laundering verification by a major international tax firm with independent legal counsel alongside. The structure was examined to that standard precisely so that none of you would ever have to wonder. You may think what you like of the man. The money is clean, and it will withstand any scrutiny anyone cares to bring to it.
What this means in practice:
Your £20 million is held in your name and remains accessible for life. It is not released on a schedule and not withheld by a guardian — a written request is the only step
Your monthly income of £20,000, index-linked and payable until seventy-five, continues on exactly the same terms. Take it, pause it, or let it accumulate — and change your mind as often as you like
Drawing nothing costs you nothing else. The villa, the vessels and every service the Trust provides remain open to you in full, on the same footing as everyone else
There is no deadline and no closing door. A beneficiary who takes nothing for forty years may make a request on an ordinary Tuesday, and it will be met without comment or condition
Two consequences follow, and they matter most for the generation after you. If you have children, their entitlement is their own: it arrives on the terms set out in this letter when they come of age, and it does not depend on whether you ever took a penny of yours. Your restraint is yours to exercise — it is not an inheritance you can pass down. And should a beneficiary reach the end of life having neither married nor had children, whatever remains undrawn returns quietly to the pool and goes on providing for the rest of the family. Nothing is forfeited, and nothing is lost.
What I am building here is meant to survive a bad afternoon, a proud gesture, and a line of reasoning that the rest of us cannot follow. Families contain all three — mine certainly does. So the Trust is built to hold everyone, including anyone who wants no part of it today, and to still be holding them in thirty years when they think again. No one is left out. Not for pride, not for principle, and not for reasons the rest of us find unusual.
"You cannot refuse this. You can only leave it untouched — and it will still be there, waiting, long after the reasons for leaving it have faded."
How This Actually Works
Who to ask, and what happens next.
Everything above is intention. This is the machinery, because a promise you cannot act on is only a sentiment.
The practical points
You do not ask me. The Trust is administered by a UK-registered professional trust company. They hold the deed, they hold the assets, and they answer to it rather than to me
Making a request. A short written request to the trustee is the whole process. You will complete identity and source-of-funds formalities once, at the beginning, and not again
Timescales. Requests are acknowledged within five working days and settled within thirty. No reason need be given for drawing your own entitlement, and none will be asked for
If a request is ever refused it will be for a legal or regulatory reason and nothing else. You are entitled to that reason in writing, and to have it reviewed independently
The next generation. Children born to any beneficiary are added to the deed automatically. Their entitlement vests at eighteen and does not depend on anything their parent did or did not do
After I am gone. Nothing changes. The deed does not need me to function, and it was written that way deliberately
If any part of this is unclear when the time comes, ask the trustee to explain it until it is. They are paid to do exactly that.
Risks and Rewards
The cost of real wealth is not money.
It is risk, and the willingness to carry it. I scraped together €29,000, lost it all. Rebuilt, lost €740,000. Watched €4.8 million evaporate. Each time, I came back. Not because I was fearless, but because I had nothing else. The work was all I had. And then one day, the pieces connected. I made more in the following four years than in the entire three decades before.
"Risk and reward go hand in hand. If you try to eliminate all risk, you eliminate all reward. The entire business world — and life in general — runs on this balance."
Prosperity for Future Generations
The vault is locked. Literally, on-chain.
Participation in the Gilding Family Trust is not a question put to you. All ten are included by deed, permanently, and so is every child born to them. There is no opt-out, no forfeiture, and no mechanism by which one generation's silence can disinherit the next.
What is locked is my own capital — bound in smart contracts that cannot be reversed or appealed, not by anyone, not even by me. Your entitlement sits inside that structure, held in your name whether you call on it early, late, or never at all.
"Let this be a moment to think not only of what you receive today, but of the legacy you leave tomorrow. The Trust exists to protect, to provide, and to preserve — so that our family's story is one of strength, unity, and opportunity, long after we are gone."
"Managed with discipline, this sum will sustain our family across generations. But this moment is about more than a number. It is proof that consistency, self-education, and the refusal to quit can take a person further than almost any other combination of advantages. I did not inherit this. I built it."
Nikolas G
Founder, Bitcoin Storm · December 2027 · Confidential — For Family